Pages

Wednesday, January 7, 2026

Terminal Tractor Market 2030: Driving the Future of Cargo Handling

The global terminal tractor market was valued at USD 752.2 million in 2023 and is expected to reach USD 1.03 billion by 2030, expanding at a CAGR of 4.7% from 2024 to 2030. Terminal tractors—also referred to as yard trucks, hostlers, or shunt trucks—are purpose-built vehicles used to move trailers and containers within confined environments such as ports, terminals, warehouses, and distribution centers.

These vehicles play a vital role in enabling efficient cargo transfers between different areas of a facility or across transportation modes, including ships, railways, and road transport. Market growth is primarily driven by the increasing need for efficient cargo-handling solutions and the rapid expansion of e-commerce and retail logistics.
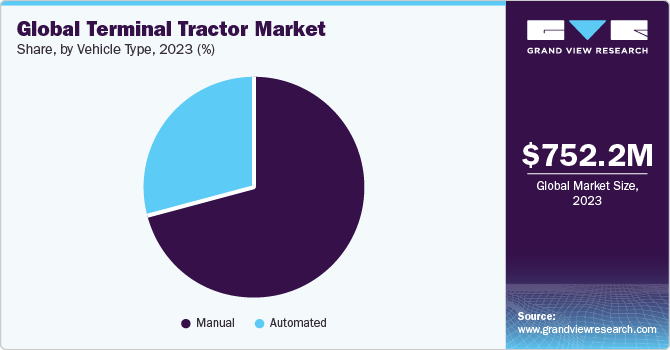
Global Terminal Tractor Market share and size, 2023

Rising global trade volumes have significantly increased the demand for streamlined cargo-handling operations across logistics and transportation hubs worldwide. As a result, terminal tractors have become indispensable assets for organizations aiming to improve productivity and operational efficiency. Optimizing the deployment and utilization of these vehicles is increasingly critical for businesses operating in ports, terminals, and logistics centers. According to the World Trade Organization (WTO), in 2022 China exported USD 100.91 billion of iron and steel, followed by Japan at USD 36.04 billion, South Korea at USD 32.47 billion, Indonesia at USD 28.42 billion, and India at USD 18.40 billion, highlighting the scale of trade activities that support demand for terminal tractors.

In parallel, the rapid growth of e-commerce platforms and evolving retail logistics models are reshaping market dynamics. As consumers increasingly rely on online shopping, the volume of goods moving through distribution centers, fulfillment hubs, and last-mile delivery facilities has surged. Terminal tractors are critical in these environments, as they enable efficient maneuvering of trailers and containers, ensuring faster movement of goods from storage areas to outbound transportation vehicles.

Order a free sample PDF of the Terminal Tractor Market Intelligence Study, published by Grand View Research.

Key Market Trends & Insights

  • North America accounted for the largest regional market share of 33.6% in 2023. The region has experienced significant growth in intermodal transportation due to its extensive transportation infrastructure. Major trade corridors, such as the Transcontinental Railroad, along with key port cities including Los Angeles, New York, and Houston, facilitate efficient multimodal goods movement. This interconnected network has enhanced cost efficiency and operational performance, driving demand for terminal tractors.
  • By drive type, the 4x2 segment dominated the market with a 41.6% share in 2023 and is expected to register the fastest CAGR during the forecast period. Terminal operators are increasingly favoring 4x2 models due to their superior fuel efficiency and operational productivity compared to heavier 6x4 alternatives. Their cost-effectiveness and alignment with sustainability goals are key factors driving adoption.
  • By propulsion, the electric segment is projected to grow at a strong CAGR throughout the forecast period. Growing environmental concerns and stricter emissions regulations are encouraging the adoption of electric terminal tractors as a cleaner alternative to diesel-powered models. In response, companies are pursuing strategic initiatives; for example, in August 2023, Kalmar, a division of Cargotec, acquired the product rights to Lonestar Specialty Vehicles’ electric terminal tractor line in the U.S., with LSV acting as a contract manufacturing partner.
  • By application, the port terminal segment led the market in 2023 and is expected to continue experiencing robust growth. The increasing use of containerization in maritime trade has amplified the need for specialized equipment to handle standardized containers. Terminal tractors play a crucial role in moving containers within terminal yards, positioning them for vessel loading, or transferring them to storage areas, thereby supporting efficient port operations.
  • By tonnage, the 50–100 ton segment is anticipated to witness substantial growth over the forecast period. Expanding industrial and manufacturing activities in sectors such as automotive, construction, and heavy machinery are driving demand for high-capacity terminal tractors capable of handling oversized and heavy loads within production and logistics facilities.
  • By vehicle type, the manual segment held the largest market share in 2023. Manually operated terminal tractors remain more cost-effective than automated or electric alternatives due to lower initial investment requirements and minimal infrastructure needs. This affordability makes them particularly attractive for operators with budget constraints or in environments where automation is not yet practical.

Market Size & Forecast

  • 2023 Market Size: USD 752.2 Million
  • 2030 Projected Market Size: USD 1.03 Billion
  • CAGR (2024-2030): 4.7%
  • North America: Largest market in 2023

Key Companies & Market Share Insights

Major players operating in the terminal tractor market include Kalmar, Konecranes, Terberg Group, and Sany Group.

  • Kalmar, part of Cargotec Corporation, provides heavy-duty material handling equipment and services for ports, terminals, and distribution centers. Its terminal tractor portfolio includes models such as Kalmar TX Electric, T2i, Ottawa T2, TR618i, and TT618i, designed to enhance cargo-handling efficiency.
  • Konecranes is a global provider of lifting equipment and material handling solutions for industries including manufacturing, ports, and terminals. Known for its focus on innovation, safety, and sustainability, the company offers terminal tractor models such as YF 230, YL 230, and RL 230.

Key Players

  • Kalmar
  • Konecranes
  • Terberg Group
  • Sany Group
  • Hyster-Yale Materials Handling
  • CVS Ferrari
  • MAFI Transport-System
  • TICO Tractors
  • Mol CY
  • Capacity Truck
  • Outrider Technologies, Inc.
  • Fernride

Explore Horizon Databook – The world's most expansive market intelligence platform developed by Grand View Research.

Conclusion

The terminal tractor market is expected to experience steady growth through 2030, driven by increasing global trade, expanding e-commerce and retail logistics, and the need for efficient cargo-handling solutions. North America remains the leading regional market, while electrification, improved fuel efficiency, and rising containerization are shaping future demand. As logistics operators continue to prioritize productivity, sustainability, and cost efficiency, terminal tractors will remain a critical component of modern port, terminal, and distribution center operations.

Solid State Cooling Market 2030: Revolutionizing Energy Efficiency

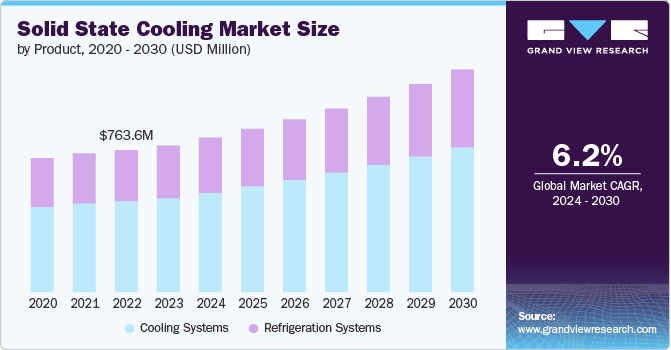
The global solid state cooling market was valued at USD 788.0 million in 2023 and is expected to grow to USD 1.20 billion by 2030, registering a CAGR of 6.2% from 2024 to 2030. This growth is primarily driven by the rising demand for energy-efficient cooling solutions and the increasing adoption of advanced cooling technologies across multiple industries.

Solid state cooling systems, including thermoelectric and magnetic refrigeration technologies, provide several advantages over conventional cooling methods. These benefits include higher energy efficiency, lower maintenance requirements, and environmentally friendly operation due to the absence of moving parts and harmful refrigerants. Demand for these systems is further supported by the growing need for compact and portable cooling solutions, particularly in consumer electronics, healthcare, and automotive applications. In addition, continuous advancements in thermoelectric materials and the development of innovative cooling technologies are expected to further stimulate market expansion.

Solid State Cooling Market Size by Product, 2020 - 2030 (USD Million)

Solid state cooling systems play a critical role across a wide range of industries by delivering precise and reliable temperature control. Their solid-state design allows for efficient cooling without mechanical components, making them suitable for applications in consumer electronics, healthcare devices, automotive systems, and other sectors that require consistent thermal management.

The market for solid state cooling systems is expected to expand steadily as progress in materials science and thermoelectric technologies continues. Ongoing innovations aimed at improving efficiency and reducing system costs are likely to overcome existing limitations and unlock new use cases. Moreover, the integration of IoT and smart technologies for real-time performance monitoring and enhanced control is anticipated to shape the future development of the market.

Order a free sample PDF of the Solid State Cooling Market Intelligence Study, published by Grand View Research.

Key Market Trends & Insights

  • Asia Pacific is witnessing strong market growth due to rapid industrialization, population growth, and increasing demand for consumer electronics and healthcare services. Expanding electronics and healthcare sectors in countries such as China, India, and Japan are key contributors to market growth. Supportive government policies promoting energy efficiency and environmental sustainability are also accelerating the adoption of solid state cooling systems in the region.
  • By product, the cooling systems segment dominated the market, accounting for 64.2% of global revenue in 2023. Solid-state cooling systems offer enhanced reliability, long operational life, and environmental advantages compared to traditional gas- and compressor-based cooling solutions. These systems operate on the Peltier effect, where electric current flow between different materials enables heat absorption or release.
  • Based on type, the single-stage solid state cooling system segment held 49.3% of global market revenue in 2023. This segment is well suited for energy-efficient and environmentally friendly cooling applications where compact size, low noise, and high reliability are essential. Its scalability and small form factor also make it attractive for integration into wearable devices, providing personal cooling in high-temperature environments.
  • By end use, the healthcare segment accounted for 49.7% of global market revenue in 2023. The healthcare industry relies heavily on solid state cooling systems for patient monitoring equipment, laboratory instruments, and medical refrigeration. Strict regulatory requirements and the need for precise temperature control are key factors driving demand in this segment.
  • In terms of technology, the thermoelectric cooling segment represented 50.1% of global market revenue in 2023. This technology is increasingly adopted due to its compact design, reliability, and environmentally friendly performance. Thermoelectric cooling aligns with global sustainability initiatives and provides precise temperature control, making it ideal for applications such as medical devices, laboratory equipment, and sensitive electronic components.

Market Size & Forecast

  • 2023 Market Size: USD 788.0 Million
  • 2030 Projected Market Size: USD 1.20 Billion
  • CAGR (2024-2030): 6.2%
  • Asia Pacific: Largest market in 2023

Key Companies & Market Share Insights

Key companies operating in the solid state cooling market include Phononic, Inc., Laird Thermal Systems, Inc., and II-VI Incorporated, along with several emerging participants.

  • Phononic, Inc. is a leading provider of solid state cooling solutions, offering a broad portfolio of thermoelectric systems for diverse applications. The company’s emphasis on innovation and advanced technologies has established its reputation for high-performance, reliable, and energy-efficient cooling solutions.
  • Laird Thermal Systems, Inc. is recognized for its high-quality thermoelectric cooling products and extensive industry expertise. Its solutions are widely used in consumer electronics, healthcare, and automotive applications that require efficient and dependable thermal management.

Emerging players such as Ferrotec Holdings Corporation and Kryotherm are also strengthening their presence in the market.

  • Ferrotec Holdings Corporation focuses on high-performance thermoelectric modules and cooling systems for industrial applications, leveraging advanced technology and quality-driven manufacturing.
  • Kryotherm offers a wide range of thermoelectric cooling solutions, with a strong emphasis on innovation and customer-focused product development, enhancing its competitive position in the market.

Key Players

  • Phononic, Inc.
  • Laird Thermal Systems, Inc.
  • II-VI Incorporated
  • Ferrotec Holdings Corporation
  • Kryotherm
  • Delta Eletronics, Inc.
  • Coheretn Corp.
  • CUI Devices
  • Micropelt GmbH
  • Thermion Company
  • RMT Ltd.
  • Mercury Systems, Inc.
  • Crystal Ltd.Achilli S.r.l

Explore Horizon Databook – The world's most expansive market intelligence platform developed by Grand View Research.

Conclusion

The solid state cooling market is positioned for steady growth, supported by increasing demand for energy-efficient, compact, and environmentally friendly cooling solutions across industries. Advancements in thermoelectric materials, expanding adoption in healthcare and consumer electronics, and strong growth in the Asia Pacific region are key factors shaping the market. As innovations continue to improve efficiency, reduce costs, and integrate smart technologies, solid state cooling systems are expected to play an increasingly important role in next-generation thermal management solutions through 2030.

Smart Speaker Market 2030: Revolutionizing Home Automation

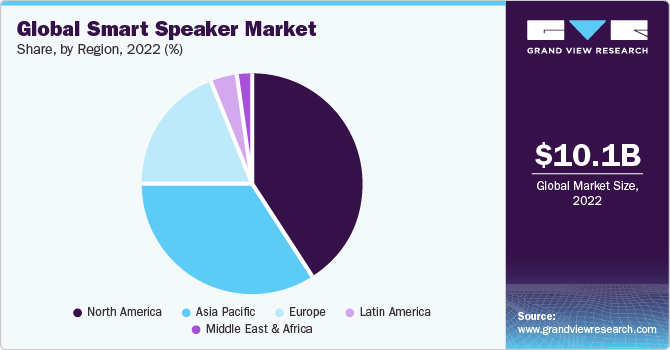
The global smart speaker market was valued at USD 10.06 billion in 2022 and is expected to expand significantly, reaching USD 50.19 billion by 2030 at a CAGR of 22.2% from 2023 to 2030. This strong growth is primarily driven by the rising adoption of smart home technologies and the increasing penetration of connected home devices, which are encouraging consumers to shift toward smart speakers as central control hubs for their homes.

One of the key factors supporting market growth is the ability of smart speakers to operate through voice commands. The convenience of controlling multiple home functions—such as lighting, appliances, entertainment, and security—from anywhere in the house using voice interaction has made these devices highly attractive to consumers. Voice assistants such as Amazon Alexa and Google Home are gaining widespread popularity. Alexa held the largest market share in 2012, followed by Google. Furthermore, Google introduced its smart speaker, Google Home, in several Asian countries, including India and Japan, and this expansion is expected to contribute to strong growth over the forecast period.

Global smart speaker Market share and size, 2022

Consumers increasingly favor cost-effective products that combine multiple advanced features. Amazon Alexa gained substantial traction through aggressive promotional strategies, including in-store marketing at Whole Foods and extensive online and television advertising campaigns. Additionally, Amazon adopted competitive pricing strategies to strengthen its market position, further accelerating adoption.

The growing automation of household tasks and rising demand for human-to-machine interaction are also expected to boost market growth in the coming years. According to data published by voicebot.ai in April 2020, nearly 88 million adults in the U.S. had installed smart speakers. This adoption is largely attributed to the multifunctional nature of these devices, which can be used for music streaming, accessing sports and entertainment updates, managing daily tasks, and controlling smart home devices.

Order a free sample PDF of the Smart Speaker Market Intelligence Study, published by Grand View Research.

Key Market Trends & Insights

  • North America dominated the smart speaker market in 2022, accounting for the largest revenue share of 41.0%. This dominance is driven by high demand for Internet-of-Things (IoT)-enabled services and wireless devices, along with a strong consumer preference for convenience products. As an early adopter of smart technologies, the region has benefited from high consumer willingness to accept and use new innovations, encouraging manufacturers to continuously introduce advanced products.
  • The Amazon Alexa segment held the largest revenue share of 36.6% in 2022. Its widespread adoption in the U.S. is supported by its first-mover advantage, extensive smart home integrations, and Amazon’s strategy of licensing Alexa to multiple emerging market players. This trend is expected to continue over the forecast period.
  • The Google Assistant segment is anticipated to experience substantial growth and is expected to emerge as a leading virtual personal assistant over the forecast period. Rapid adoption in Asia, supported by product launches in countries such as India and Japan, is a major growth driver. In China, however, the market is characterized by strong competition from domestic players such as Alibaba, Xiaomi, and JD.com.
  • The Apple Siri segment is projected to grow at the fastest CAGR of 31.2% during the forecast period. Apple’s strong brand loyalty plays a critical role in driving adoption, as existing Apple users are more likely to choose HomePod or HomePod mini devices. Improvements in Siri’s voice recognition accuracy and reliability, combined with the superior sound quality of Apple’s smart speakers, have enhanced their appeal, particularly among users focused on music and podcast consumption.

Market Size & Forecast

  • 2022 Market Size: USD 10.06 Billion
  • 2030 Projected Market Size: USD 50.19 Billion
  • CAGR (2023-2030): 22.2%
  • North America: Largest market in 2022
  • Asia Pacific: Fastest growing market

Key Companies & Market Share Insights

Major players operating in the smart speaker market include Amazon, Google, Apple, and Xiaomi. These companies are actively focusing on upgrading existing product lines, investing in technological advancements, and forming strategic collaborations to strengthen their market presence.

In December 2021, Google launched the Nest Audio smart speaker, which features advanced sound optimization capabilities. The Media EQ feature automatically adjusts audio output based on the type of content being played, while Ambient IQ modifies volume levels according to background noise. Nest Audio can also be connected with other Nest or Google Home devices to enable a seamless multi-room audio experience.

Key Players

  • Apple, Inc.
  • Amazon.com, Inc.
  • Bose Corporation
  • Baidu, Inc
  • Google LLC
  • HARMAN International
  • Sonos, Inc.
  • ULTIMATE EARS
  • Sony Corporation
  • Panasonic Holdings Corporation
  • Xiaomi

Explore Horizon Databook – The world's most expansive market intelligence platform developed by Grand View Research.

Conclusion

The smart speaker market is poised for rapid expansion, driven by the growing adoption of smart home ecosystems, increasing consumer demand for voice-controlled convenience, and continuous advancements in virtual personal assistant technologies. Strong growth in North America, rising adoption across Asia Pacific, and aggressive innovation by key players such as Amazon, Google, and Apple are shaping the competitive landscape. As smart speakers continue to evolve with improved voice recognition, better sound quality, and deeper integration with connected devices, they are expected to play an increasingly central role in modern smart homes through 2030.

Semiconductor Metrology And Inspection Equipment Market: Navigating the Future of Precision

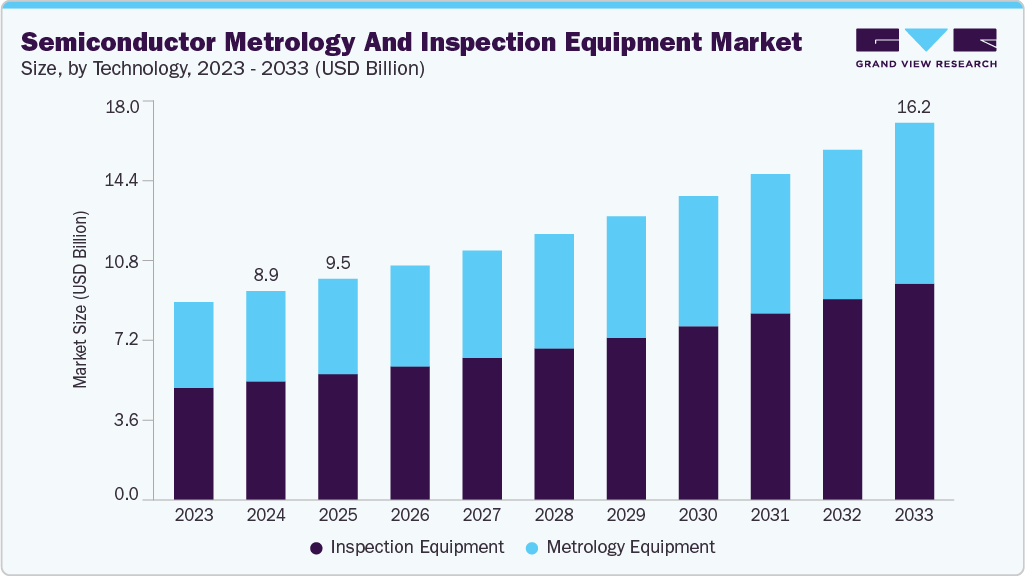
The global semiconductor metrology and inspection equipment market was valued at USD 8.98 billion in 2024 and is expected to grow to USD 16.21 billion by 2033, reflecting a CAGR of 6.9% from 2025 to 2033. This growth is largely driven by the increasing complexity of semiconductor devices, such as FinFETs, Gate-All-Around (GAA) transistors, and 3D NAND architectures, which demand advanced metrology and inspection tools to ensure optimal yield and performance.

Additionally, the rising adoption of EUV (Extreme Ultraviolet) lithography, increased investments in sub-7nm process technologies, and the expansion of global semiconductor fabrication (fab) capacity, particularly in Asia-Pacific and North America, are contributing to the growing need for high-precision in-line and 3D metrology systems.

Semiconductor metrology and inspection equipment market size and growth forecast (2023-2033)

A significant factor fueling this growth is the U.S. government's investment in semiconductor technology through the CHIPS & Science Act. Since 2022, the Act has allocated over USD 100 million toward advanced metrology research and an additional USD 300 million for next-generation packaging metrology, in collaboration with the National Institute of Standards and Technology (NIST) and Manufacturing USA. These initiatives are supporting the development of inspection tools capable of handling sub-5 nm geometries, promoting domestic manufacturing and strengthening R&D in semiconductor technologies. This funding is accelerating innovation and commercializing cutting-edge metrology solutions.

Another important factor driving growth in the semiconductor metrology market is the increasing emphasis on standardized, traceable measurements. Leading organizations like Germany’s PTB, the UK’s NPL, and the U.S. NIST are working to create robust calibration systems for semiconductor applications across a range of wavelengths, from EUV to infrared. PTB’s Metrology Light Source (MLS) facility, for example, plays a crucial role in enabling high-accuracy calibration for semiconductor tools. These traceability efforts are enhancing consistency across global fab environments and improving interoperability, which in turn is boosting the adoption of metrology and inspection systems worldwide.

Order a free sample PDF of the Semiconductor Metrology And Inspection Equipment Market Intelligence Study, published by Grand View Research.

Key Market Trends & Insights

  • Asia Pacific led the semiconductor metrology and inspection equipment market with a 54.7% revenue share in 2024. This dominance is driven by rapid fab expansions and increased investment in advanced process nodes across Taiwan, South Korea, China, and Japan. Government-backed technology roadmaps and industrial policies have turned the Asia Pacific region into a hub for semiconductor equipment procurement, especially for tools focused on 3D inspection, high-throughput metrology, and EUV mask analysis.
  • Inspection Equipment was the largest market segment, accounting for 56.8% of revenue in 2024. The need for early defect detection in advanced manufacturing nodes is propelling this demand. Optical and electron beam inspection systems are critical for identifying defects during lithography and etching, which are key for maintaining high yield and throughput, especially as devices shrink.
  • 2D Metrology/Inspection tools dominated the market in 2024 but are expected to see slower growth as the industry shifts toward more complex 3D architectures. These tools are still crucial for legacy and mid-range process nodes (28 nm and above) but will face increasing competition from 3D-based solutions as chip designs become more vertically integrated.
  • The ≤ 7 nm process node segment was the largest revenue driver in 2024. This segment is growing due to the increasing demand for precision in applications like high-performance computing (HPC), artificial intelligence (AI), and mobile systems on chips (SoCs). As the industry moves toward 5 nm, 3 nm, and eventually 2 nm nodes, the need for advanced inspection and metrology tools to handle line-edge roughness, pattern collapse, and EUV mask defects will continue to grow.
  • Foundries accounted for the largest market revenue share by fab type in 2024, driven by the diverse customer applications and the continuous migration of technology to advanced nodes. Leading foundries are adopting new metrology and inspection tools to support a wide range of technologies, from mature process nodes to cutting-edge geometries.

Market Size & Forecast

  • 2024 Market Size: USD 8.98 Billion
  • 2033 Projected Market Size: USD 16.21 Billion
  • CAGR (2025-2033): 6.9%
  • Asia Pacific: Largest market in 2024

Key Companies & Market Share Insights

Notable players in the semiconductor metrology and inspection equipment market include KLA Corporation, Applied Materials, Inc., Hitachi High-Tech Corporation, and ASML. These companies are investing heavily in developing advanced tools for sub-7 nm and 3D packaging nodes. As semiconductor device architectures become more complex, with new challenges such as gate-all-around FETs and chiplet integration, these companies are pushing the boundaries of precision measurement, offering atomic-scale resolution and real-time defect classification.

  • KLA Corporation is a global leader in semiconductor metrology, with a diverse portfolio that includes optical and electron beam inspection, critical dimension scanning electron microscopy (CD-SEM), overlay metrology, and defect review systems. KLA is also at the forefront of AI-driven analytics and real-time defect classification for sub-5 nm and 3D chip architectures.
  • Applied Materials, Inc. is another key player offering integrated metrology and inspection solutions. The company’s innovations in inline measurement systems using advanced optics, quantum sensors, and AI algorithms help monitor and control critical parameters during chip fabrication. Applied is also focusing on next-generation technologies, such as gate-all-around transistors and 3D packaging, to enhance yield and process accuracy.

Key Players

  • Applied Materials, Inc.
  • ASML
  • Camtek
  • Hitachi High-Tech Corporation
  • KLA Corporation
  • Lasertec Corporation
  • Nova Ltd.
  • Onto Innovation
  • SCREEN Semiconductor Solutions Co., Ltd.
  • Thermo Fisher Scientific Inc.

Explore Horizon Databook – The world's most expansive market intelligence platform developed by Grand View Research.

Conclusion

The semiconductor metrology and inspection equipment market is on a strong growth trajectory, driven by the increasing complexity of chip architectures and advancements in process technologies. As the industry progresses toward smaller process nodes and more intricate device structures, the demand for high-precision metrology and inspection tools will continue to grow. Key market drivers include government investments, such as the U.S. CHIPS & Science Act, and the push for standardized, traceable measurements to ensure consistency across global semiconductor fabs. Leading companies in the sector are adapting to these trends by developing next-generation solutions that support the shift to sub-7 nm nodes, 3D packaging, and advanced defect detection.

Tuesday, January 6, 2026

Rice Bran Oil Market 2030: A Golden Future in Health and Wellness

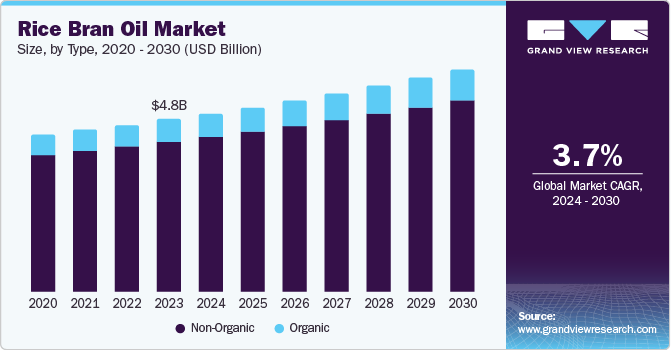
The global rice bran oil market was valued at USD 4.85 billion in 2023 and is projected to reach USD 6.25 billion by 2030, expanding at a CAGR of 3.7% from 2024 to 2030. Rice bran oil is extracted from the outer layer of rice grains, specifically the bran and germ, and has gained widespread acceptance due to its nutritional benefits and excellent cooking performance.

Rice bran oil is increasingly favored for its health-related properties, as it contains unsaturated fats, antioxidants, vitamins, and other bioactive compounds that make it suitable for cooking and food processing applications. Rising consumer awareness regarding health and wellness, a growing preference for natural and organic products, and expansion of the global food industry are key factors supporting market growth.

Rice Bran Oil Market Size, by Type, 2020 - 2030 (USD Billion)

One of the key advantages of rice bran oil is its high smoke point of approximately 450°F, which makes it ideal for deep frying and high-temperature cooking. The oil is also rich in oryzanol, a compound associated with cholesterol reduction. In addition, it contains tocopherols (vitamin E) and tocotrienols, which play an important role in antioxidant activity. As consumers become more health-conscious, demand for nutritionally rich edible oils such as rice bran oil continues to rise.

The growing shift toward natural and organic food products is further supporting market expansion, as consumers become increasingly aware of the potential health risks associated with synthetic additives and preservatives. Rice bran oil addresses this demand by being positioned as a healthier alternative to conventional cooking oils. Its mild flavor profile allows it to be used across a wide range of culinary applications, including frying, sautéing, and salad dressings, making it popular among both professional chefs and home cooks.

Order a free sample PDF of the Rice Bran Oil Market Intelligence Study, published by Grand View Research.

Key Market Trends & Insights

  • Asia Pacific dominated the global rice bran oil market with a revenue share of 37.8% in 2023. This dominance is driven by abundant rice production, rising health awareness, and growing preference for healthier cooking oils in countries such as India and China. Increasing disposable income and rapid urbanization are further boosting demand for premium edible oils. Additionally, rice bran oil’s versatility across food, cosmetic, and pharmaceutical applications enhances its market potential. However, challenges such as inconsistent oil quality and limited consumer awareness in certain segments may restrain growth.
  • By Type, the non-organic segment accounted for the largest revenue share of 87.0% in 2023 and is expected to continue dominating the market during the forecast period. The strong performance of this segment is attributed to its affordability, wide availability through established supply chains, effective marketing strategies emphasizing versatility and cost-effectiveness, the absence of regulatory preference for organic products, and its broad usage across multiple industries.
  • By Application, the nutraceutical segment is expected to register the fastest CAGR from 2024 to 2030. Growth in this segment is supported by the strong nutritional profile of rice bran oil, which is rich in unsaturated fatty acids such as oleic acid, known for its cardiovascular benefits. The presence of bioactive compounds including oryzanol, tocopherols, tocotrienols, and phytosterols further contributes to its increasing use in dietary supplements and functional foods.
  • By Distribution Channel, the offline segment is expected to grow at the fastest CAGR during the forecast period. Consumers often prefer purchasing food products from physical retail stores, as this allows for direct interaction with store staff and immediate product availability. Established brick-and-mortar outlets continue to inspire greater consumer trust, particularly for essential cooking ingredients like edible oils.

Market Size & Forecast

  • 2023 Market Size: USD 4.85 Billion
  • 2030 Projected Market USD 6.25 Billion
  • CAGR (2024-2030): 3.7%
  • Asia Pacific: Largest market in 2023
  • North America: Fastest growing market

Key Companies & Market Share Insights

Key players operating in the rice bran oil market include Adani Group, Modi Naturals, Marico, King Rice Oil Group, and others. Companies are focusing on expanding their customer base and strengthening market presence through strategic initiatives such as mergers and acquisitions and partnerships with other major organizations.

  • King Rice Oil Group has been specializing in high-quality rice bran oil for more than four decades. The company produces refined rice bran oil, crude rice bran oil, and defatted rice bran, exporting its products to over 30 countries. Its offerings are rich in natural antioxidants such as oryzanol and vitamin E, positioning it as a leading player in the global rice bran oil market.
  • Marico markets rice bran oil under its well-known Saffola brand. The company offers blended refined edible oils that combine rice bran oil with other vegetable oils such as safflower, corn, and soybean oils. Marico emphasizes the health benefits of rice bran oil, highlighting its antioxidant content and role in supporting heart health, catering specifically to health-conscious consumers.

Key Players

  • Adani Group
  • Modi Naturals
  • Marico
  • CONAGRA BRANDS, INC
  • King Rice Oil Group
  • Ricela Health Foods Ltd.
  • 3F Industries LTD
  • Sethia Oils Ltd

Explore Horizon Databook – The world's most expansive market intelligence platform developed by Grand View Research.

Conclusion

The rice bran oil market is expected to witness steady growth through 2030, supported by increasing health awareness, rising demand for natural and nutritionally rich edible oils, and expanding applications in food and nutraceutical sectors. Asia Pacific will continue to lead the market due to strong rice production and growing consumer preference for healthier cooking alternatives, while North America is expected to experience the fastest growth. With its high smoke point, mild flavor, and proven health benefits, rice bran oil is well positioned to maintain its relevance and expand its presence in the global edible oils market.

Release Liner Market 2030: Innovations Shaping the Future

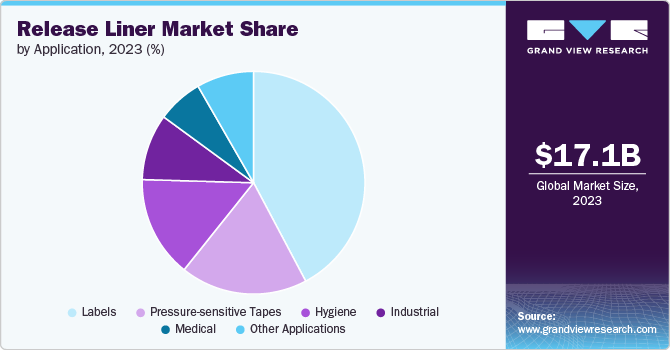
The global release liner market was valued at USD 17.08 billion in 2023 and is projected to reach USD 28.52 billion by 2030, expanding at a CAGR of 6.6% from 2024 to 2030. This growth is primarily driven by increasing demand from key end-use industries, including medical, industrial, packaging and labeling, and hygiene applications.

Rising demand for labeling across sectors such as food and beverages, pharmaceuticals, and logistics has been a major factor supporting the adoption of release liners. In addition, the growing need for advanced wound care products and medical adhesives is contributing to market expansion. The use of release liners is also increasing in automotive, electronics, and construction industries, where pressure-sensitive tapes and adhesive products are widely used. Economic growth in regions such as Asia Pacific has led to higher levels of construction and industrial activity, particularly in automotive and electronics manufacturing, further driving global demand for release liners.

Release Liner Market Share by Application, 2023 (%)

The shift toward pressure-sensitive labels in packaging, logistics, and branding applications is another important growth driver. These labels are preferred for their ease of application, flexibility, and performance, which in turn increases the demand for high-quality release liners. Moreover, the rapid expansion of e-commerce has significantly boosted the need for efficient packaging and labeling solutions. Release liners play a critical role in maintaining label quality, durability, and performance, thereby supporting market growth.

However, fluctuations in the prices of raw materials such as silicone and paper can affect production costs and profit margins for manufacturers. Environmental concerns related to the disposal and recycling of release liners also pose challenges, as increasing regulatory pressure aims to reduce waste and improve recyclability. Additionally, the growing adoption of digital labeling and printing technologies may limit demand for traditional release liners in certain applications.

Order a free sample PDF of the Release Liner Market Intelligence Study, published by Grand View Research.

Key Market Trends & Insights

  • Asia Pacific dominated the release liner market in 2023, accounting for a revenue share of 34.6%, and is expected to continue growing at a strong pace over the forecast period. Increased infrastructure development and technological advancements in the region have led to higher consumption of release liners across applications such as self-adhesive products and high-performance films.
  • By Material Type, the silicone segment held the largest market share of 63.6% in 2023 and is anticipated to grow significantly over the forecast period. Silicone-based release liners offer consistent and reliable release performance and can withstand high temperatures and chemical exposure. These properties make them well-suited for pressure-sensitive labels, adhesive tapes, and medical adhesive products, where stability and hypoallergenic characteristics are critical.
  • By Application, the label segment accounted for the largest revenue share of 41.4% in 2023 and is expected to grow at the fastest rate during the forecast period. Release liners used in labeling applications are widely utilized across food and beverages, personal care, and household products. Demand is driven by the need for durable, visually appealing labels that can withstand various environmental conditions, while release liners help preserve label integrity during storage and application.

Market Size & Forecast

  • 2023 Market Size: USD 17.08 Billion
  • 2030 Projected Market USD 28.52 Billion
  • CAGR (2024-2030): 6.6%
  • Asia Pacific: Largest market in 2023

Key Companies & Market Share Insights

Major companies operating in the release liner market include 3M, Dow, and Ahlstrom.

  • 3M operates through four primary business segments: safety and industrial, transportation and electronics, healthcare, and consumer. The company has manufacturing and sales operations in more than 70 countries across North America, Europe, Asia Pacific, and the Middle East & Africa. Founded in 1929, 3M is headquartered in the United States.
  • Dow manufactures a wide range of chemicals, plastics, and agricultural products and serves markets such as agriculture, automotive, building and construction, energy and water, electronic materials, packaging, industrial, and infrastructure. The company operates through 32 subsidiaries, including Arabian Chemical Company Ltd., Blue Cube Holding LLC, CD Polymers, DOCOMO, Inc., Dow Business Services, and Dow Chemical China Holdings Pte. Ltd.

Emerging participants in the market include Mondi and Felix Schoeller.

  • Mondi produces containerboard and converted corrugated solutions, along with a diverse portfolio that includes flexible packaging, bags and pouches, release liners, functional films, industrial bags, barrier coatings, specialty kraft paper, and printing papers.
  • Felix Schoeller focuses on the production, development, and marketing of specialty papers for digital printing, self-adhesive applications, photographic uses, and packaging. Its product portfolio includes décor papers, photographic and digital printing papers, release liners, sublimation papers, and other specialty paper solutions.

Key Players

  • Dow
  • Loparex
  • 3M
  • Mondi
  • Ahlstrom
  • Elkem ASA
  • Felix Schoeller
  • Gascogne Group
  • LINTEC Corporation
  • Sappi Group

Explore Horizon Databook – The world's most expansive market intelligence platform developed by Grand View Research.

Conclusion

The release liner market is expected to experience steady growth through 2030, supported by rising demand from packaging, labeling, medical, and industrial sectors. Strong growth in Asia Pacific, increasing adoption of pressure-sensitive labels, and the expansion of e-commerce are key factors driving market expansion. While raw material price volatility and environmental concerns pose challenges, ongoing innovation in recyclable and biodegradable materials is creating new opportunities. As sustainability becomes a central focus across industries, the development of eco-friendly release liners is likely to play a crucial role in shaping the future of the global market.

Recycled Carbon Fiber Market: Reinventing Sustainability in Manufacturing

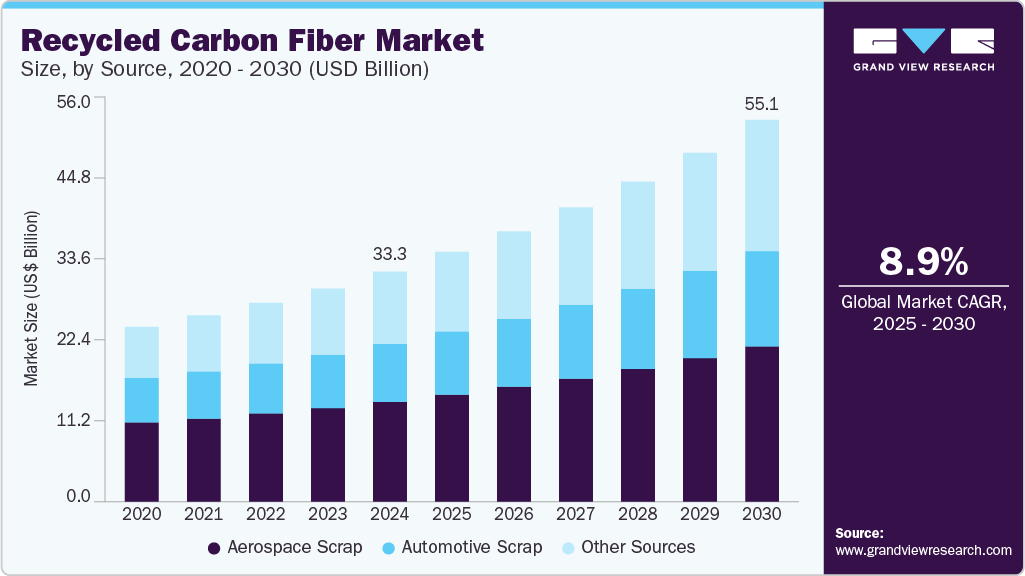
The global recycled carbon fiber market was valued at USD 33.31 billion in 2024 and is projected to reach USD 55.11 billion by 2030, registering a CAGR of 8.9% from 2025 to 2030. Market growth is primarily driven by the rising global focus on sustainability and the circular economy, which is encouraging industries to reduce waste generation and lower their carbon footprints.

Recycled carbon fiber is increasingly viewed as a viable alternative to virgin carbon fiber, as it delivers comparable performance characteristics at a significantly lower cost. Major end-use industries such as automotive, aerospace, wind energy, and sporting goods are progressively adopting recycled carbon fiber, largely due to its lightweight nature and favorable strength-to-weight ratio.

Recycled Carbon Fiber Market

For example, in April 2024, UBE Corporation introduced new composite materials incorporating recycled carbon fiber. These products were developed by integrating recycled carbon fiber into various nylon formulations and enhancing their functional properties. The composites are intended for use in industries including automotive and sports, with the goal of reducing component weight, improving performance, lowering energy consumption, and decreasing greenhouse gas emissions associated with conventional carbon fiber production.

Ongoing technological advancements are improving recycling methods and enhancing the quality and efficiency of reclaimed carbon fibers. Pyrolysis, which involves heating carbon composites in an oxygen-free environment to remove resin, remains a widely used technique. Recent innovations, such as microwave-assisted recycling, have significantly reduced energy consumption. In March 2025, the Fraunhofer Institute for High-Speed Dynamics developed an advanced pyrolysis process designed to recycle carbon fibers from thermosetting composites. This process efficiently recovers fibers—particularly continuous carbon fiber rovings used in high-pressure hydrogen tanks—while preserving their mechanical properties.

Order a free sample PDF of the Recycled Carbon Fiber Market Intelligence Study, published by Grand View Research.

Key Market Trends & Insights

  • Asia Pacific accounted for the largest revenue share of 28.6% in 2024, supported by a strong industrial base and extensive consumer goods manufacturing. Growing demand for lightweight, high-performance materials across multiple sectors is driving adoption, as recycled carbon fiber offers both economic and environmental advantages. In the aerospace sector, although virgin carbon fiber continues to dominate critical applications, increasing emphasis on sustainability and cost reduction is encouraging the use of recycled carbon fiber in non-critical components.
  • By Source, the aerospace scrap segment led the market with a revenue share of 43.3% in 2024. This segment includes pre-consumer manufacturing waste such as offcuts from fuselage sections, wing spars, and structural components, as well as end-of-life aircraft parts. Due to stringent aerospace performance standards, these materials are made from high-quality carbon fiber composites, which retain strong mechanical properties even after recycling.
  • By Type, the chopped fiber segment dominated the market in 2024. Chopped recycled carbon fiber is highly versatile and widely used in injection molding, compounding, and non-woven mat applications. Its ease of integration into thermoplastic and thermoset matrices enables the production of lightweight and high-strength composite materials, making it a preferred option for manufacturers seeking sustainable alternatives without sacrificing performance.
  • By End Use, the automotive and transportation segment held the dominant market position in 2024. Rising demand for lightweight, fuel-efficient, and environmentally sustainable materials is accelerating the use of recycled carbon fiber in this sector. With a strength-to-weight ratio comparable to virgin fiber and a significantly lower cost and environmental impact, recycled carbon fiber presents a strong value proposition. Notably, Asahi Kasei, in collaboration with the National Institute of Technology, Kitakyushu College, and Tokyo University of Science, achieved a major advancement in continuous carbon fiber recycling technology under a project supported by NEDO.

Market Size & Forecast

  • 2024 Market Size: USD 33.31 Billion
  • 2030 Projected Market Size: USD 55.11 Billion
  • CAGR (2025-2030): 8.9%
  • Asia Pacific: Largest market in 2024
  • Middle East & Africa: Fastest growing market

Key Companies & Market Share Insights

Key players operating in the recycled carbon fiber market include Toray Industries, Inc., Mitsubishi Chemical Holdings Corporation, Procotex Corporation SA, among others. Companies are focusing on expanding their customer base to strengthen their competitive positioning. Strategic initiatives such as mergers and acquisitions, capacity expansions, and product innovations are being undertaken to align with evolving regulations and sustainability goals.

  • Toray Industries, Inc. is a leading player in advanced materials with extensive expertise in carbon fiber and composites. The company is actively developing and commercializing recycled carbon fiber solutions, including products derived from aerospace manufacturing waste.
  • Procotex Corporation SA, a Belgium-based sustainable fiber supplier, specializes in recycling and processing various textile waste streams, including carbon fibers. Through its subsidiary ELG CARBON FIBER LTD., the company offers a wide range of recycled carbon fiber products under brands such as CARBISO C, CARBISO MLD, and CARBISO P.

Key Players

  • TORAY INDUSTRIES, INC.
  • Mitsubishi Chemical Group Corporation.
  • Procotex
  • Carbon Fiber Remanufacturing
  • Sigmatex
  • Gen 2 Carbon Limited
  • SGL Carbon
  • TEIJIN LIMITED
  • Carbon Conversions
  • Alpha Recyclage Composites

Explore Horizon Databook – The world's most expansive market intelligence platform developed by Grand View Research.

Conclusion

The recycled carbon fiber market is set to experience robust growth through 2030, driven by increasing sustainability initiatives, cost advantages over virgin materials, and continuous advancements in recycling and manufacturing technologies. Strong demand from automotive, aerospace, and industrial applications, combined with improving fiber quality and broader applicability, is accelerating market adoption. With Asia Pacific leading the market and the Middle East & Africa emerging as the fastest-growing region, recycled carbon fiber is expected to play a critical role in supporting lightweight, high-performance, and environmentally responsible material solutions across global industries.

Real World Evidence Solutions Market: Unlocking Insights Beyond Clinical Trials

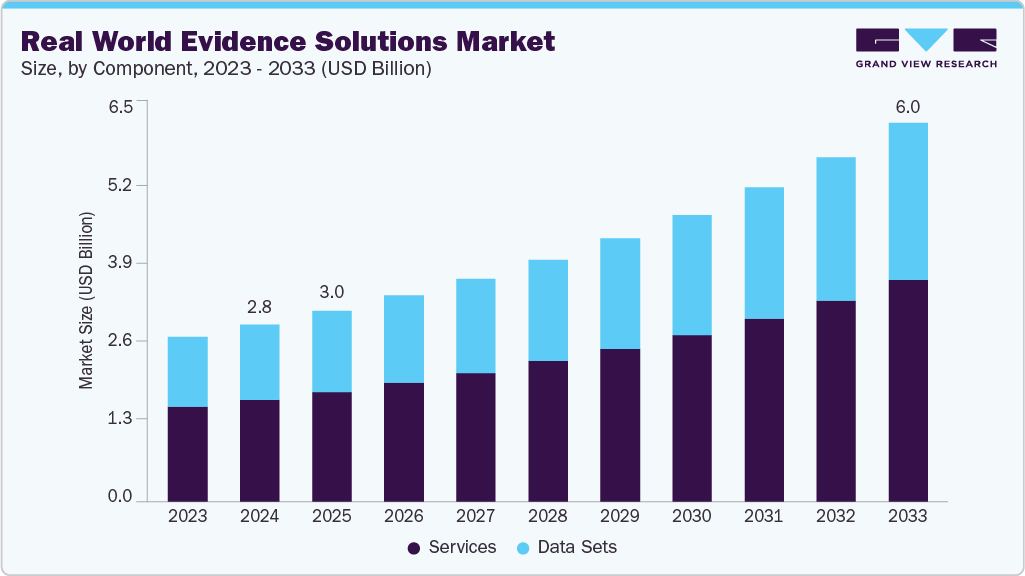
The global real-world evidence (RWE) solutions market was valued at USD 2.81 billion in 2024 and is expected to reach USD 6.01 billion by 2033, growing at a CAGR of 8.94% from 2025 to 2033. Market growth is driven by rising R&D expenditure, expanding applications of real-world evidence across multiple healthcare domains, increasing regulatory support for the use of RWE solutions, and the rapidly growing volume of real-world data.

Real world evidence solutions market size and growth forecast (2023-2033)

Growing regulatory acceptance of real-world evidence is a major factor supporting market expansion. Regulatory agencies worldwide are providing clearer guidance on how real-world data (RWD) can be used to support product approvals, label expansions, and post-market evaluations. This improved regulatory clarity reduces compliance risks and encourages pharmaceutical and biotechnology companies to invest in advanced RWE platforms. Key regulatory initiatives facilitating RWE adoption include:

  • FDA (U.S.) – Through the 21st Century Cures Act and dedicated RWE guidance, the FDA defines how electronic health records, claims data, and registries can be used in regulatory submissions, along with requirements for data quality and methodological validation.
  • EMA (EU) – The EMA’s DARWIN EU network, RWE Roadmap, and Data Quality Framework standardize the use of RWD across Europe, enabling consistent integration of RWE throughout the product lifecycle.
  • MHRA (UK) – The MHRA provides detailed guidance on RWD-based studies and randomized controlled trials using RWD, specifying acceptable data sources, endpoints, and safety processes through its RWE Scientific Dialogue pathway.
  • PMDA (Japan) – The PMDA emphasizes data reliability and analytical rigor while increasingly accepting registry-based evidence for approvals and label updates, particularly in rare and pediatric indications.

These regulatory initiatives are strengthening industry confidence in real-world evidence methodologies, thereby accelerating the global adoption of RWE solutions.

The rapid growth in the volume of real-world data is another key driver of the RWE solutions market. Health-related data is expanding at a compound annual growth rate of approximately 36%, driven by the widespread use of electronic health records, insurance claims, disease registries, wearable devices, and patient-reported outcomes. Advances in data integration, interoperability, and analytics enable RWE platforms to convert these large and complex datasets into actionable insights. This capability allows pharmaceutical companies, payers, and healthcare providers to generate more accurate and timely evidence to support drug development, regulatory decision-making, and value-based care models.

Order a free sample PDF of the Real World Evidence Solutions Market Intelligence Study, published by Grand View Research.

Key Market Trends & Insights

  • North America dominated the real-world evidence solutions market with a revenue share of 43.17% in 2024. This leadership is supported by strong regulatory backing for RWE use, increasing R&D investments, and the ongoing transition from volume-based to value-based healthcare. The presence of major RWE solution providers in the U.S. and Canada, along with favorable government policies and a growing number of service providers, further contributes to regional market growth.
  • By Component, the services segment held the largest market share of 57.73% in 2024. High adoption of real-world evidence services by pharmaceutical and biotechnology companies and healthcare providers is a major factor driving this segment. Strategic initiatives by industry players also support growth. For example, in February 2024, Gilead Sciences, Inc. announced plans to present real-world evidence and new clinical data from its antiviral R&D programs at the 31st Conference on Retroviruses and Opportunistic Infections (CROI 2024).
  • By Application, the drug development and approvals segment accounted for the largest revenue share of 28.61% in 2024. RWE solutions support efficient operational management and accelerate drug development and approval timelines for pharmaceutical companies, healthcare providers, and payers. Government initiatives further promote the use of RWE in medical device development and approvals. For instance, in December 2023, the FDA released draft guidance describing its evaluation of RWD in medical device clearance and approval decisions, supported by anonymized case examples.
  • By Therapeutic Area, the oncology segment held the largest revenue share of 22.93% in 2024. Growth in this segment is driven by the extensive use of RWE in cancer drug development to reduce clinical trial costs, improve regulatory success rates, and shorten approval timelines. According to GLOBOCAN, approximately 10.0 million new cancer cases and 9.7 million cancer-related deaths were recorded globally in 2022. In India, cancer incidence increased from 1.39 million cases in 2020 to 1.46 million cases in 2022, as reported by the Indian Council of Medical Research. The rising global cancer burden continues to accelerate the adoption of RWE solutions in oncology research.
  • By End Use, healthcare companies held the dominant market share in 2024. This growth is attributed to the increasing importance of RWE studies in drug approvals, the need to minimize costly drug recalls, and the growing demand to assess product performance in real-world clinical settings. For example, in February 2024, PINC AI Applied Sciences, a division of Premier, Inc., and Datavant expanded their collaboration to strengthen healthcare research, enhance clinical trial operations, and promote trial diversity and equity.

Market Size & Forecast

  • 2024 Market Size: USD 2.81 Billion
  • 2033 Projected Market Size: USD 6.01 Billion
  • CAGR (2025-2033): 8.94%
  • North America: Largest market in 2024
  • Asia Pacific: Fastest growing market

Key Companies & Market Share Insights

Key participants in the real-world evidence solutions market are adopting advanced strategies such as AI-driven analytics, predictive modeling, patient stratification, and automated outcomes reporting to improve research efficiency and decision-making. Integration with interoperable healthcare IT systems, electronic health records, claims databases, and collaborations with biopharmaceutical companies, payers, and research organizations are further expanding the adoption and reach of RWE solutions.

Key Players

  • IQVIA
  • Merative
  • PPD Inc. (now part of Thermo Fisher)
  • Parexel International Corporation
  • NTT DATA, Inc.
  • Icon Plc
  • Oracle
  • Syneos Health
  • Cegedim Health Data
  • Medpace
  • Optum Inc. (UnitedHealth Group)
  • SAS Institute Inc.
  • Cognizant
  • Aetion, Inc. (acquired by Datavant in May 2025)
  • Flatiron Health
  • Cytel Inc.
  • Trinity

Explore Horizon Databook – The world's most expansive market intelligence platform developed by Grand View Research.

Conclusion

The real-world evidence solutions market is poised for sustained growth through 2033, supported by increasing regulatory acceptance, rising R&D investments, and the exponential growth of healthcare data. Continued advancements in analytics, interoperability, and AI-enabled platforms are enhancing the value of RWE across drug development, regulatory decision-making, and real-world clinical evaluation. With North America maintaining market leadership and Asia Pacific emerging as the fastest-growing region, RWE solutions are expected to play an increasingly critical role in shaping data-driven, value-based healthcare worldwide.

Quantum Computing Software Market: Revolutionizing Tech with Quantum Power

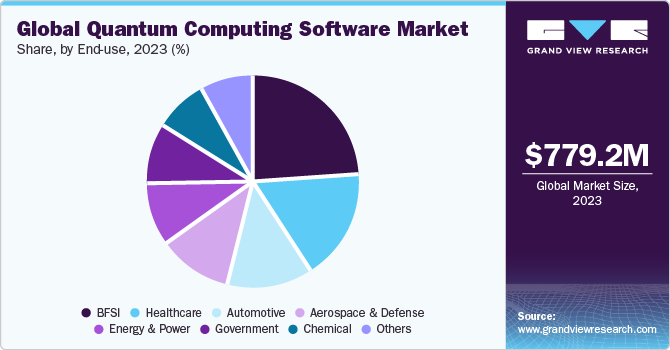
The global quantum computing software market was valued at USD 779.2 million in 2023 and is expected to reach USD 2.51 billion by 2030, expanding at a CAGR of 18.5% from 2024 to 2030. Market growth is being driven by the rapid development of customized quantum software solutions designed to address specific application needs across multiple industries.

In drug discovery, quantum chemistry software enables highly accurate simulations of molecular structures, while quantum optimization algorithms are increasingly applied to complex supply chain and logistics challenges. In addition, quantum machine learning libraries are being developed to leverage the computational advantages of quantum systems to enhance artificial intelligence models. These tailored software solutions are designed to solve industry-specific problems and deliver more precise and efficient outcomes compared to traditional computing methods.

Global Quantum Computing Software market share and size, 2023

Quantum computing technology also enables the development of ultra-precise and highly personalized medical and diagnostic tools. For example, quantum sensors can deliver extremely accurate measurements in magnetic resonance imaging (MRI) systems, contributing to improvements in diagnostic quality. Applications in healthcare include optimizing radiation therapy, modeling protein structures, developing personalized cancer treatments, and advancing DNA analysis. These capabilities have the potential to significantly enhance the overall quality and effectiveness of healthcare services.

Alongside these developments, cloud ecosystems are evolving as major technology companies and quantum vendors expand their quantum offerings. Software tools, application programming interfaces (APIs), and quantum development kits are increasingly being integrated into existing cloud platforms. This approach aims to make quantum computing resources more accessible and user-friendly for developers, researchers, and enterprises. By democratizing access to quantum capabilities, this trend supports collaborative development, experimentation, and faster innovation within quantum ecosystems.

Order a free sample PDF of the Quantum Computing Software Market Intelligence Study, published by Grand View Research.

Key Market Trends & Insights

  • North America led the quantum computing software market in 2023, accounting for 34.2% of the global share. In the United States, strong government support through initiatives such as the National Quantum Initiative Act has resulted in substantial funding for quantum research and development. This has attracted significant private investment into companies such as Google, IBM, and emerging startups. Similarly, Canada has demonstrated a strong commitment to quantum technologies through funding programs such as the Strategic Innovation Fund and collaborative efforts involving federal and provincial governments as well as academic institutions.
  • By Component, the services segment dominated the market, contributing 63.6% of global revenue in 2023. The rapid growth of cloud-based quantum computing services has enabled remote access to quantum hardware, algorithms, and development environments. These platforms reduce barriers to adoption, allowing researchers and developers to experiment with quantum algorithms and accelerating innovation while expanding access to quantum technologies.
  • By Deployment, the cloud segment captured the largest revenue share in 2023. Quantum computing providers are increasingly offering cloud-based platforms, such as D-Wave’s Leap, which allow users to access quantum processors, simulators, and development tools remotely. This deployment model supports broader adoption by lowering infrastructure costs and enabling a wider range of users to develop and deploy quantum applications.
  • By Technology, superconducting qubits accounted for the largest market revenue share in 2023. Ongoing advancements in materials, fabrication techniques, and control mechanisms have supported increases in qubit counts while improving stability and reducing error rates. Research efforts have also focused on advanced error-correction techniques, such as surface codes, to improve computational accuracy and move beyond the noisy intermediate-scale quantum (NISQ) stage.
  • By Application, the machine learning segment is expected to register the fastest CAGR during the forecast period. Growth is supported by the development of quantum-inspired neural networks, particularly for medical image analysis. These models are designed to reflect quantum principles, enabling more efficient data processing and the identification of subtle patterns that may be overlooked by classical machine learning approaches. In March 2023, QC Ware reported results from a collaborative research initiative with a leading biotechnology company, demonstrating improved detection accuracy and classification of diabetic retinopathy using quantum computing techniques.
  • By End-use, the BFSI sector led the market in 2023. Financial institutions are increasingly adopting quantum computing to enhance transaction speeds, trading performance, and data processing efficiency. Simulation-based applications, particularly in financial risk management, are a key area of interest. Compared to classical systems, quantum computing can significantly reduce processing time and operational costs, enabling more efficient risk modeling and opening new revenue opportunities.

Market Size & Forecast

  • 2023 Market Size: USD 779.2 Million
  • 2030 Projected Market Size: USD 2.51 Billion
  • CAGR (2024-2030):18.5%
  • North America: Largest market in 2023

Key Companies & Market Share Insights

Key players operating in the quantum computing software market include Microsoft Corporation, IBM Corporation, QC Ware, and Google LLC (Alphabet Inc.).

  • IBM Corporation offers a comprehensive portfolio of quantum software solutions, led by Qiskit, an open-source quantum software development kit (SDK) that supports quantum program development and execution. IBM also provides tools such as Quantum Composer and Quantum Lab, which enable users to design and simulate quantum circuits and advance quantum algorithm research. These solutions, combined with IBM Quantum Experience, deliver cloud-based access to quantum processors and foster experimentation and innovation.
  • QC Ware provides a broad range of quantum computing software solutions, including quantum algorithms, optimization tools, and quantum machine learning applications. Its flagship product, Forge, enables the creation and deployment of quantum algorithms tailored to industrial use cases, supporting advanced simulations and complex problem-solving across multiple sectors.

Key Players

  • 1QBIT
  • Accenture PLC
  • AWS Inc.
  • Cambridge Quantum Computing
  • D-Wave Systems
  • Fujitsu Ltd.
  • Google LLC
  • Honeywell Inc.
  • Huawei Technology Co. Ltd.
  • IBM Corporation
  • Microsoft Corporation
  • QC Ware
  • Rigetti Computing
  • Riverlane
  • Zapata Computing

Explore Horizon Databook – The world's most expansive market intelligence platform developed by Grand View Research.

Conclusion

The quantum computing software market is positioned for strong growth through 2030, driven by increasing demand for industry-specific quantum applications, expanding healthcare and financial use cases, and the rapid evolution of cloud-based quantum platforms. Continued investments in superconducting qubit technologies, quantum machine learning, and cloud deployment models are expected to accelerate adoption and innovation. With North America leading the market and major technology providers expanding their software ecosystems, quantum computing software is set to play a transformative role across industries in the coming years.

Pressure Transmitter Market 2030: Innovations Transforming Industrial Automation

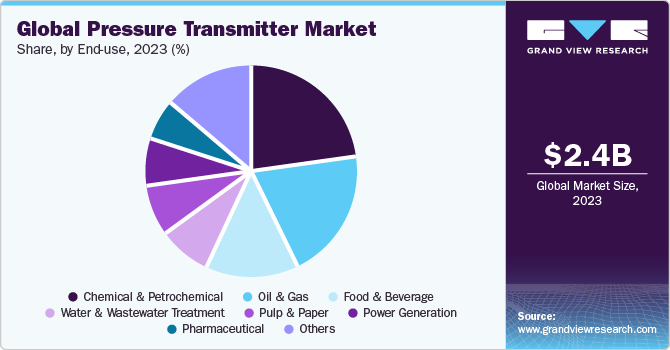
The global pressure transmitter market was valued at USD 2,401.6 million in 2023 and is expected to reach USD 3,132.1 million by 2030, registering a CAGR of 3.9% from 2024 to 2030. Market growth is primarily driven by the rising need for accurate, reliable, and consistent pressure measurement across a wide range of industrial applications.

Pressure transmitters are extensively used in industries such as oil and gas, chemical and petrochemical, and power generation. Growing demand across upstream, midstream, and downstream oil and gas operations—including wellhead pressure monitoring, pipeline surveillance, and refinery processing—is a major factor supporting market expansion.

Global Pressure Transmitter market share and size, 2023

In addition, the increasing adoption of Industry 4.0, along with the shift toward smart factories in the U.S., is contributing to market growth. The introduction of advanced pressure transmitters equipped with features such as wireless communication, digital interfaces, and remote monitoring capabilities is further strengthening demand, particularly in technologically advanced industrial environments.

The need for precise and reliable pressure measurement solutions is also increasing in chemical processing applications. According to the American Chemistry Council, the U.S. chemical industry generated USD 639 billion in revenue in 2022. This industry produces a broad range of products, including plastics, synthetic fibers, fertilizers, pharmaceuticals, and specialty chemicals. High levels of innovation and substantial investments in research and development continue to drive demand for advanced instrumentation, including pressure transmitters. These factors are expected to support sustained market growth over the forecast period.

Order a free sample PDF of the Pressure Transmitter Market Intelligence Study, published by Grand View Research.

Key Market Trends & Insights

  • Asia Pacific accounted for the largest revenue share of 46.9% in 2023. Growth in the region is driven by rapid digitalization and the increasing adoption of the industrial Internet of Things (IIoT), which requires advanced sensors capable of real-time data transmission. Rising industrialization, increasing automation, and significant infrastructure investments further support market expansion. Major manufacturing hubs such as China, Japan, and India play a crucial role in driving regional growth.
  • By Type, the differential-pressure transmitter segment dominated the market with a revenue share of 51.24% in 2023. These transmitters are widely used for measuring flow, level, and pressure differences across various industrial processes. Their ability to withstand mechanical stress, vibrations, and harsh operating conditions makes them well-suited for industrial environments. Availability in multiple configurations and customization options further enhances their adoption.
  • By Sensing Technology, the piezoresistive segment led the market with a revenue share of 46.4% in 2023. Piezoresistive pressure transmitters are valued for their accuracy, durability, and reliability and are widely used in industries such as oil and gas, automotive, aerospace, medical, and chemical processing. Their suitability for harsh environments is expected to drive continued demand.
  • By End Use, the oil and gas segment held the largest revenue share of 20.43% in 2023. Pressure transmitters play a critical role in ensuring safe and efficient operations across oil and gas facilities, including offshore platforms and storage tanks. Increasing emphasis on operational safety and process efficiency continues to support market growth in this segment.
  • By Fluid Type, the liquid segment dominated the market with a revenue share of 70.71% in 2023. Pressure transmitters are widely used to measure pressure in liquids across industries such as chemicals, pharmaceuticals, food and beverage, water and wastewater treatment, and oil and gas. Their ability to handle corrosive and abrasive fluids in both hazardous and non-hazardous environments drives strong adoption.
  • By Application, the pressure measurement segment accounted for the largest revenue share of 49.51% in 2023. These transmitters are designed to deliver high accuracy, fast response times, and reliability. Advanced features such as digital communication protocols, temperature compensation, and self-diagnostics contribute to their widespread use in industrial processes.

Market Size & Forecast

  • 2023 Market Size: USD 2,401.6 Million
  • 2030 Projected Market Size: USD 3,132.1 Million
  • CAGR (2024-2030): 3.9%
  • Asia Pacific: Largest market in 2023

Key Companies & Market Share Insights

The global pressure transmitter market is highly competitive, with the presence of both global and regional manufacturers. Companies are focusing on growth strategies such as mergers and acquisitions, joint ventures, and product innovation. Products are distributed through multiple channels, including distributors, company-owned platforms, retailers, and e-commerce. For example, in November 2022, Emerson launched a new line of Rosemount 3051 pressure transmitters designed to deliver enhanced accuracy and reliability in harsh environments, featuring advanced diagnostics and wireless capabilities for easier installation and maintenance.

Key Players

  • ABB Group
  • Siemens
  • Schneider Electric SE
  • Hitachi, Company limited
  • Honeywell International
  • Yokogawa Electric Corp
  • Emerson Electric Company
  • The Danfoss Group
  • Fuji Electric Co ltd v, Ltd.
  • TE Connectivity Ltd
  • Zemic Group
  • Anfield Sensors Inc
  • Endress+Hauser AG
  • LCM Systems Limited
  • SOR Controls Group

Explore Horizon Databook – The world's most expansive market intelligence platform developed by Grand View Research.

Conclusion

The pressure transmitter market is expected to experience steady growth through 2030, supported by increasing industrial automation, rising demand for precise pressure measurement, and the adoption of smart manufacturing technologies. Strong demand from the oil and gas and chemical industries, combined with advancements in sensing technologies and digital connectivity, will continue to shape market development. Asia Pacific is set to remain the dominant region, while ongoing product innovation and strategic expansions by key players will further strengthen the market’s growth trajectory.