Pages

Tuesday, January 6, 2026

Release Liner Market 2030: Innovations Shaping the Future

The global release liner market was valued at USD 17.08 billion in 2023 and is projected to reach USD 28.52 billion by 2030, expanding at a CAGR of 6.6% from 2024 to 2030. This growth is primarily driven by increasing demand from key end-use industries, including medical, industrial, packaging and labeling, and hygiene applications.

Rising demand for labeling across sectors such as food and beverages, pharmaceuticals, and logistics has been a major factor supporting the adoption of release liners. In addition, the growing need for advanced wound care products and medical adhesives is contributing to market expansion. The use of release liners is also increasing in automotive, electronics, and construction industries, where pressure-sensitive tapes and adhesive products are widely used. Economic growth in regions such as Asia Pacific has led to higher levels of construction and industrial activity, particularly in automotive and electronics manufacturing, further driving global demand for release liners.
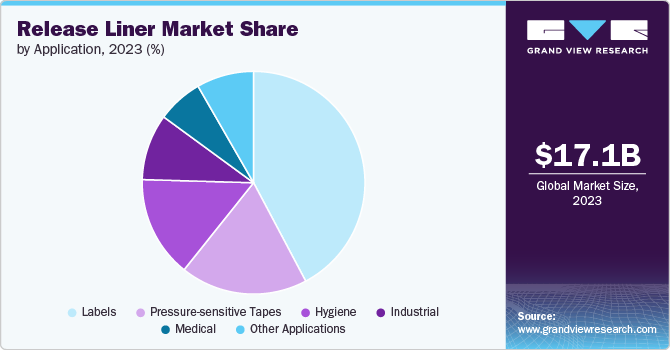
Release Liner Market Share by Application, 2023 (%)

The shift toward pressure-sensitive labels in packaging, logistics, and branding applications is another important growth driver. These labels are preferred for their ease of application, flexibility, and performance, which in turn increases the demand for high-quality release liners. Moreover, the rapid expansion of e-commerce has significantly boosted the need for efficient packaging and labeling solutions. Release liners play a critical role in maintaining label quality, durability, and performance, thereby supporting market growth.

However, fluctuations in the prices of raw materials such as silicone and paper can affect production costs and profit margins for manufacturers. Environmental concerns related to the disposal and recycling of release liners also pose challenges, as increasing regulatory pressure aims to reduce waste and improve recyclability. Additionally, the growing adoption of digital labeling and printing technologies may limit demand for traditional release liners in certain applications.

Order a free sample PDF of the Release Liner Market Intelligence Study, published by Grand View Research.

Key Market Trends & Insights

  • Asia Pacific dominated the release liner market in 2023, accounting for a revenue share of 34.6%, and is expected to continue growing at a strong pace over the forecast period. Increased infrastructure development and technological advancements in the region have led to higher consumption of release liners across applications such as self-adhesive products and high-performance films.
  • By Material Type, the silicone segment held the largest market share of 63.6% in 2023 and is anticipated to grow significantly over the forecast period. Silicone-based release liners offer consistent and reliable release performance and can withstand high temperatures and chemical exposure. These properties make them well-suited for pressure-sensitive labels, adhesive tapes, and medical adhesive products, where stability and hypoallergenic characteristics are critical.
  • By Application, the label segment accounted for the largest revenue share of 41.4% in 2023 and is expected to grow at the fastest rate during the forecast period. Release liners used in labeling applications are widely utilized across food and beverages, personal care, and household products. Demand is driven by the need for durable, visually appealing labels that can withstand various environmental conditions, while release liners help preserve label integrity during storage and application.

Market Size & Forecast

  • 2023 Market Size: USD 17.08 Billion
  • 2030 Projected Market USD 28.52 Billion
  • CAGR (2024-2030): 6.6%
  • Asia Pacific: Largest market in 2023

Key Companies & Market Share Insights

Major companies operating in the release liner market include 3M, Dow, and Ahlstrom.

  • 3M operates through four primary business segments: safety and industrial, transportation and electronics, healthcare, and consumer. The company has manufacturing and sales operations in more than 70 countries across North America, Europe, Asia Pacific, and the Middle East & Africa. Founded in 1929, 3M is headquartered in the United States.
  • Dow manufactures a wide range of chemicals, plastics, and agricultural products and serves markets such as agriculture, automotive, building and construction, energy and water, electronic materials, packaging, industrial, and infrastructure. The company operates through 32 subsidiaries, including Arabian Chemical Company Ltd., Blue Cube Holding LLC, CD Polymers, DOCOMO, Inc., Dow Business Services, and Dow Chemical China Holdings Pte. Ltd.

Emerging participants in the market include Mondi and Felix Schoeller.

  • Mondi produces containerboard and converted corrugated solutions, along with a diverse portfolio that includes flexible packaging, bags and pouches, release liners, functional films, industrial bags, barrier coatings, specialty kraft paper, and printing papers.
  • Felix Schoeller focuses on the production, development, and marketing of specialty papers for digital printing, self-adhesive applications, photographic uses, and packaging. Its product portfolio includes décor papers, photographic and digital printing papers, release liners, sublimation papers, and other specialty paper solutions.

Key Players

  • Dow
  • Loparex
  • 3M
  • Mondi
  • Ahlstrom
  • Elkem ASA
  • Felix Schoeller
  • Gascogne Group
  • LINTEC Corporation
  • Sappi Group

Explore Horizon Databook – The world's most expansive market intelligence platform developed by Grand View Research.

Conclusion

The release liner market is expected to experience steady growth through 2030, supported by rising demand from packaging, labeling, medical, and industrial sectors. Strong growth in Asia Pacific, increasing adoption of pressure-sensitive labels, and the expansion of e-commerce are key factors driving market expansion. While raw material price volatility and environmental concerns pose challenges, ongoing innovation in recyclable and biodegradable materials is creating new opportunities. As sustainability becomes a central focus across industries, the development of eco-friendly release liners is likely to play a crucial role in shaping the future of the global market.

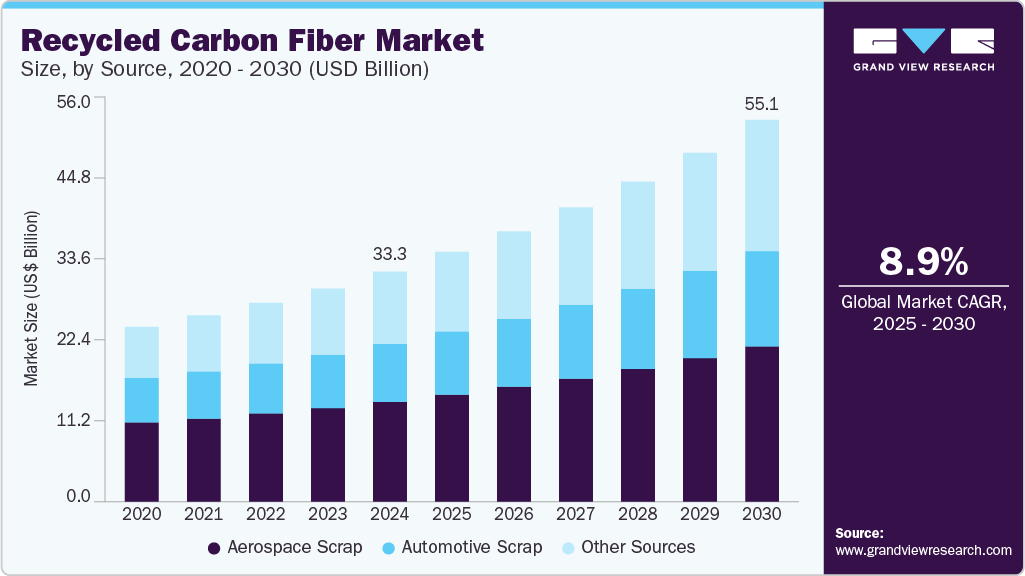
Recycled Carbon Fiber Market: Reinventing Sustainability in Manufacturing

The global recycled carbon fiber market was valued at USD 33.31 billion in 2024 and is projected to reach USD 55.11 billion by 2030, registering a CAGR of 8.9% from 2025 to 2030. Market growth is primarily driven by the rising global focus on sustainability and the circular economy, which is encouraging industries to reduce waste generation and lower their carbon footprints.

Recycled carbon fiber is increasingly viewed as a viable alternative to virgin carbon fiber, as it delivers comparable performance characteristics at a significantly lower cost. Major end-use industries such as automotive, aerospace, wind energy, and sporting goods are progressively adopting recycled carbon fiber, largely due to its lightweight nature and favorable strength-to-weight ratio.

Recycled Carbon Fiber Market

For example, in April 2024, UBE Corporation introduced new composite materials incorporating recycled carbon fiber. These products were developed by integrating recycled carbon fiber into various nylon formulations and enhancing their functional properties. The composites are intended for use in industries including automotive and sports, with the goal of reducing component weight, improving performance, lowering energy consumption, and decreasing greenhouse gas emissions associated with conventional carbon fiber production.

Ongoing technological advancements are improving recycling methods and enhancing the quality and efficiency of reclaimed carbon fibers. Pyrolysis, which involves heating carbon composites in an oxygen-free environment to remove resin, remains a widely used technique. Recent innovations, such as microwave-assisted recycling, have significantly reduced energy consumption. In March 2025, the Fraunhofer Institute for High-Speed Dynamics developed an advanced pyrolysis process designed to recycle carbon fibers from thermosetting composites. This process efficiently recovers fibers—particularly continuous carbon fiber rovings used in high-pressure hydrogen tanks—while preserving their mechanical properties.

Order a free sample PDF of the Recycled Carbon Fiber Market Intelligence Study, published by Grand View Research.

Key Market Trends & Insights

  • Asia Pacific accounted for the largest revenue share of 28.6% in 2024, supported by a strong industrial base and extensive consumer goods manufacturing. Growing demand for lightweight, high-performance materials across multiple sectors is driving adoption, as recycled carbon fiber offers both economic and environmental advantages. In the aerospace sector, although virgin carbon fiber continues to dominate critical applications, increasing emphasis on sustainability and cost reduction is encouraging the use of recycled carbon fiber in non-critical components.
  • By Source, the aerospace scrap segment led the market with a revenue share of 43.3% in 2024. This segment includes pre-consumer manufacturing waste such as offcuts from fuselage sections, wing spars, and structural components, as well as end-of-life aircraft parts. Due to stringent aerospace performance standards, these materials are made from high-quality carbon fiber composites, which retain strong mechanical properties even after recycling.
  • By Type, the chopped fiber segment dominated the market in 2024. Chopped recycled carbon fiber is highly versatile and widely used in injection molding, compounding, and non-woven mat applications. Its ease of integration into thermoplastic and thermoset matrices enables the production of lightweight and high-strength composite materials, making it a preferred option for manufacturers seeking sustainable alternatives without sacrificing performance.
  • By End Use, the automotive and transportation segment held the dominant market position in 2024. Rising demand for lightweight, fuel-efficient, and environmentally sustainable materials is accelerating the use of recycled carbon fiber in this sector. With a strength-to-weight ratio comparable to virgin fiber and a significantly lower cost and environmental impact, recycled carbon fiber presents a strong value proposition. Notably, Asahi Kasei, in collaboration with the National Institute of Technology, Kitakyushu College, and Tokyo University of Science, achieved a major advancement in continuous carbon fiber recycling technology under a project supported by NEDO.

Market Size & Forecast

  • 2024 Market Size: USD 33.31 Billion
  • 2030 Projected Market Size: USD 55.11 Billion
  • CAGR (2025-2030): 8.9%
  • Asia Pacific: Largest market in 2024
  • Middle East & Africa: Fastest growing market

Key Companies & Market Share Insights

Key players operating in the recycled carbon fiber market include Toray Industries, Inc., Mitsubishi Chemical Holdings Corporation, Procotex Corporation SA, among others. Companies are focusing on expanding their customer base to strengthen their competitive positioning. Strategic initiatives such as mergers and acquisitions, capacity expansions, and product innovations are being undertaken to align with evolving regulations and sustainability goals.

  • Toray Industries, Inc. is a leading player in advanced materials with extensive expertise in carbon fiber and composites. The company is actively developing and commercializing recycled carbon fiber solutions, including products derived from aerospace manufacturing waste.
  • Procotex Corporation SA, a Belgium-based sustainable fiber supplier, specializes in recycling and processing various textile waste streams, including carbon fibers. Through its subsidiary ELG CARBON FIBER LTD., the company offers a wide range of recycled carbon fiber products under brands such as CARBISO C, CARBISO MLD, and CARBISO P.

Key Players

  • TORAY INDUSTRIES, INC.
  • Mitsubishi Chemical Group Corporation.
  • Procotex
  • Carbon Fiber Remanufacturing
  • Sigmatex
  • Gen 2 Carbon Limited
  • SGL Carbon
  • TEIJIN LIMITED
  • Carbon Conversions
  • Alpha Recyclage Composites

Explore Horizon Databook – The world's most expansive market intelligence platform developed by Grand View Research.

Conclusion

The recycled carbon fiber market is set to experience robust growth through 2030, driven by increasing sustainability initiatives, cost advantages over virgin materials, and continuous advancements in recycling and manufacturing technologies. Strong demand from automotive, aerospace, and industrial applications, combined with improving fiber quality and broader applicability, is accelerating market adoption. With Asia Pacific leading the market and the Middle East & Africa emerging as the fastest-growing region, recycled carbon fiber is expected to play a critical role in supporting lightweight, high-performance, and environmentally responsible material solutions across global industries.

Real World Evidence Solutions Market: Unlocking Insights Beyond Clinical Trials

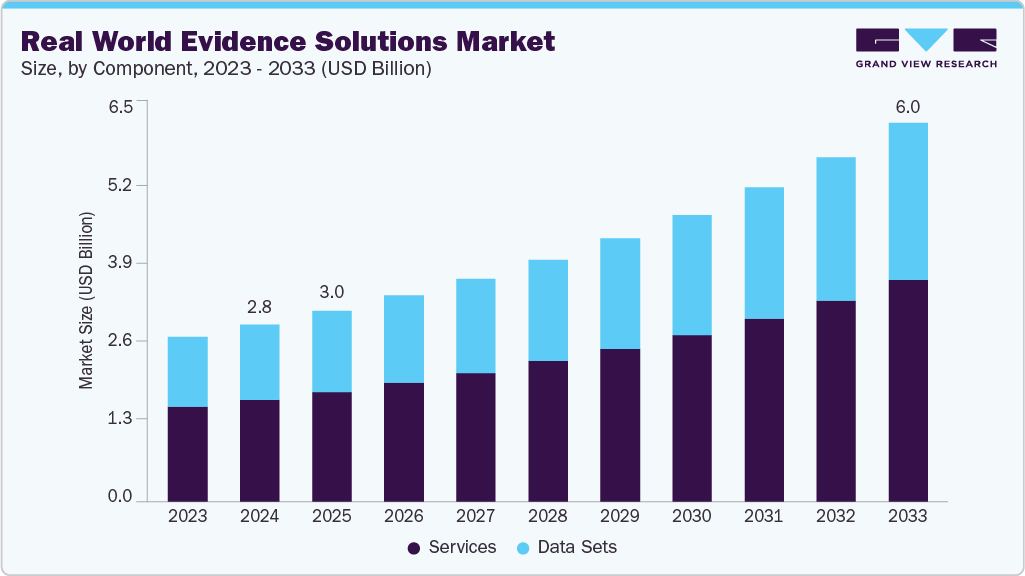
The global real-world evidence (RWE) solutions market was valued at USD 2.81 billion in 2024 and is expected to reach USD 6.01 billion by 2033, growing at a CAGR of 8.94% from 2025 to 2033. Market growth is driven by rising R&D expenditure, expanding applications of real-world evidence across multiple healthcare domains, increasing regulatory support for the use of RWE solutions, and the rapidly growing volume of real-world data.

Real world evidence solutions market size and growth forecast (2023-2033)

Growing regulatory acceptance of real-world evidence is a major factor supporting market expansion. Regulatory agencies worldwide are providing clearer guidance on how real-world data (RWD) can be used to support product approvals, label expansions, and post-market evaluations. This improved regulatory clarity reduces compliance risks and encourages pharmaceutical and biotechnology companies to invest in advanced RWE platforms. Key regulatory initiatives facilitating RWE adoption include:

  • FDA (U.S.) – Through the 21st Century Cures Act and dedicated RWE guidance, the FDA defines how electronic health records, claims data, and registries can be used in regulatory submissions, along with requirements for data quality and methodological validation.
  • EMA (EU) – The EMA’s DARWIN EU network, RWE Roadmap, and Data Quality Framework standardize the use of RWD across Europe, enabling consistent integration of RWE throughout the product lifecycle.
  • MHRA (UK) – The MHRA provides detailed guidance on RWD-based studies and randomized controlled trials using RWD, specifying acceptable data sources, endpoints, and safety processes through its RWE Scientific Dialogue pathway.
  • PMDA (Japan) – The PMDA emphasizes data reliability and analytical rigor while increasingly accepting registry-based evidence for approvals and label updates, particularly in rare and pediatric indications.

These regulatory initiatives are strengthening industry confidence in real-world evidence methodologies, thereby accelerating the global adoption of RWE solutions.

The rapid growth in the volume of real-world data is another key driver of the RWE solutions market. Health-related data is expanding at a compound annual growth rate of approximately 36%, driven by the widespread use of electronic health records, insurance claims, disease registries, wearable devices, and patient-reported outcomes. Advances in data integration, interoperability, and analytics enable RWE platforms to convert these large and complex datasets into actionable insights. This capability allows pharmaceutical companies, payers, and healthcare providers to generate more accurate and timely evidence to support drug development, regulatory decision-making, and value-based care models.

Order a free sample PDF of the Real World Evidence Solutions Market Intelligence Study, published by Grand View Research.

Key Market Trends & Insights

  • North America dominated the real-world evidence solutions market with a revenue share of 43.17% in 2024. This leadership is supported by strong regulatory backing for RWE use, increasing R&D investments, and the ongoing transition from volume-based to value-based healthcare. The presence of major RWE solution providers in the U.S. and Canada, along with favorable government policies and a growing number of service providers, further contributes to regional market growth.
  • By Component, the services segment held the largest market share of 57.73% in 2024. High adoption of real-world evidence services by pharmaceutical and biotechnology companies and healthcare providers is a major factor driving this segment. Strategic initiatives by industry players also support growth. For example, in February 2024, Gilead Sciences, Inc. announced plans to present real-world evidence and new clinical data from its antiviral R&D programs at the 31st Conference on Retroviruses and Opportunistic Infections (CROI 2024).
  • By Application, the drug development and approvals segment accounted for the largest revenue share of 28.61% in 2024. RWE solutions support efficient operational management and accelerate drug development and approval timelines for pharmaceutical companies, healthcare providers, and payers. Government initiatives further promote the use of RWE in medical device development and approvals. For instance, in December 2023, the FDA released draft guidance describing its evaluation of RWD in medical device clearance and approval decisions, supported by anonymized case examples.
  • By Therapeutic Area, the oncology segment held the largest revenue share of 22.93% in 2024. Growth in this segment is driven by the extensive use of RWE in cancer drug development to reduce clinical trial costs, improve regulatory success rates, and shorten approval timelines. According to GLOBOCAN, approximately 10.0 million new cancer cases and 9.7 million cancer-related deaths were recorded globally in 2022. In India, cancer incidence increased from 1.39 million cases in 2020 to 1.46 million cases in 2022, as reported by the Indian Council of Medical Research. The rising global cancer burden continues to accelerate the adoption of RWE solutions in oncology research.
  • By End Use, healthcare companies held the dominant market share in 2024. This growth is attributed to the increasing importance of RWE studies in drug approvals, the need to minimize costly drug recalls, and the growing demand to assess product performance in real-world clinical settings. For example, in February 2024, PINC AI Applied Sciences, a division of Premier, Inc., and Datavant expanded their collaboration to strengthen healthcare research, enhance clinical trial operations, and promote trial diversity and equity.

Market Size & Forecast

  • 2024 Market Size: USD 2.81 Billion
  • 2033 Projected Market Size: USD 6.01 Billion
  • CAGR (2025-2033): 8.94%
  • North America: Largest market in 2024
  • Asia Pacific: Fastest growing market

Key Companies & Market Share Insights

Key participants in the real-world evidence solutions market are adopting advanced strategies such as AI-driven analytics, predictive modeling, patient stratification, and automated outcomes reporting to improve research efficiency and decision-making. Integration with interoperable healthcare IT systems, electronic health records, claims databases, and collaborations with biopharmaceutical companies, payers, and research organizations are further expanding the adoption and reach of RWE solutions.

Key Players

  • IQVIA
  • Merative
  • PPD Inc. (now part of Thermo Fisher)
  • Parexel International Corporation
  • NTT DATA, Inc.
  • Icon Plc
  • Oracle
  • Syneos Health
  • Cegedim Health Data
  • Medpace
  • Optum Inc. (UnitedHealth Group)
  • SAS Institute Inc.
  • Cognizant
  • Aetion, Inc. (acquired by Datavant in May 2025)
  • Flatiron Health
  • Cytel Inc.
  • Trinity

Explore Horizon Databook – The world's most expansive market intelligence platform developed by Grand View Research.

Conclusion

The real-world evidence solutions market is poised for sustained growth through 2033, supported by increasing regulatory acceptance, rising R&D investments, and the exponential growth of healthcare data. Continued advancements in analytics, interoperability, and AI-enabled platforms are enhancing the value of RWE across drug development, regulatory decision-making, and real-world clinical evaluation. With North America maintaining market leadership and Asia Pacific emerging as the fastest-growing region, RWE solutions are expected to play an increasingly critical role in shaping data-driven, value-based healthcare worldwide.

Quantum Computing Software Market: Revolutionizing Tech with Quantum Power

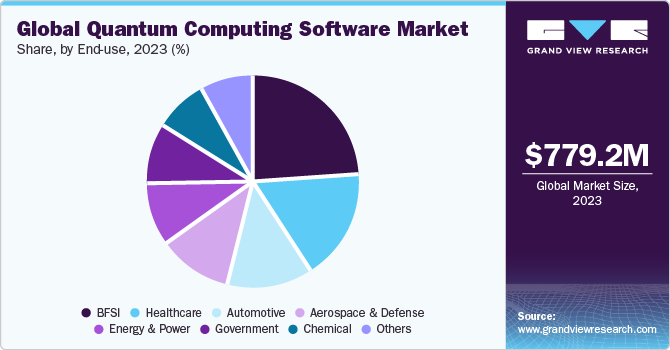
The global quantum computing software market was valued at USD 779.2 million in 2023 and is expected to reach USD 2.51 billion by 2030, expanding at a CAGR of 18.5% from 2024 to 2030. Market growth is being driven by the rapid development of customized quantum software solutions designed to address specific application needs across multiple industries.

In drug discovery, quantum chemistry software enables highly accurate simulations of molecular structures, while quantum optimization algorithms are increasingly applied to complex supply chain and logistics challenges. In addition, quantum machine learning libraries are being developed to leverage the computational advantages of quantum systems to enhance artificial intelligence models. These tailored software solutions are designed to solve industry-specific problems and deliver more precise and efficient outcomes compared to traditional computing methods.

Global Quantum Computing Software market share and size, 2023

Quantum computing technology also enables the development of ultra-precise and highly personalized medical and diagnostic tools. For example, quantum sensors can deliver extremely accurate measurements in magnetic resonance imaging (MRI) systems, contributing to improvements in diagnostic quality. Applications in healthcare include optimizing radiation therapy, modeling protein structures, developing personalized cancer treatments, and advancing DNA analysis. These capabilities have the potential to significantly enhance the overall quality and effectiveness of healthcare services.

Alongside these developments, cloud ecosystems are evolving as major technology companies and quantum vendors expand their quantum offerings. Software tools, application programming interfaces (APIs), and quantum development kits are increasingly being integrated into existing cloud platforms. This approach aims to make quantum computing resources more accessible and user-friendly for developers, researchers, and enterprises. By democratizing access to quantum capabilities, this trend supports collaborative development, experimentation, and faster innovation within quantum ecosystems.

Order a free sample PDF of the Quantum Computing Software Market Intelligence Study, published by Grand View Research.

Key Market Trends & Insights

  • North America led the quantum computing software market in 2023, accounting for 34.2% of the global share. In the United States, strong government support through initiatives such as the National Quantum Initiative Act has resulted in substantial funding for quantum research and development. This has attracted significant private investment into companies such as Google, IBM, and emerging startups. Similarly, Canada has demonstrated a strong commitment to quantum technologies through funding programs such as the Strategic Innovation Fund and collaborative efforts involving federal and provincial governments as well as academic institutions.
  • By Component, the services segment dominated the market, contributing 63.6% of global revenue in 2023. The rapid growth of cloud-based quantum computing services has enabled remote access to quantum hardware, algorithms, and development environments. These platforms reduce barriers to adoption, allowing researchers and developers to experiment with quantum algorithms and accelerating innovation while expanding access to quantum technologies.
  • By Deployment, the cloud segment captured the largest revenue share in 2023. Quantum computing providers are increasingly offering cloud-based platforms, such as D-Wave’s Leap, which allow users to access quantum processors, simulators, and development tools remotely. This deployment model supports broader adoption by lowering infrastructure costs and enabling a wider range of users to develop and deploy quantum applications.
  • By Technology, superconducting qubits accounted for the largest market revenue share in 2023. Ongoing advancements in materials, fabrication techniques, and control mechanisms have supported increases in qubit counts while improving stability and reducing error rates. Research efforts have also focused on advanced error-correction techniques, such as surface codes, to improve computational accuracy and move beyond the noisy intermediate-scale quantum (NISQ) stage.
  • By Application, the machine learning segment is expected to register the fastest CAGR during the forecast period. Growth is supported by the development of quantum-inspired neural networks, particularly for medical image analysis. These models are designed to reflect quantum principles, enabling more efficient data processing and the identification of subtle patterns that may be overlooked by classical machine learning approaches. In March 2023, QC Ware reported results from a collaborative research initiative with a leading biotechnology company, demonstrating improved detection accuracy and classification of diabetic retinopathy using quantum computing techniques.
  • By End-use, the BFSI sector led the market in 2023. Financial institutions are increasingly adopting quantum computing to enhance transaction speeds, trading performance, and data processing efficiency. Simulation-based applications, particularly in financial risk management, are a key area of interest. Compared to classical systems, quantum computing can significantly reduce processing time and operational costs, enabling more efficient risk modeling and opening new revenue opportunities.

Market Size & Forecast

  • 2023 Market Size: USD 779.2 Million
  • 2030 Projected Market Size: USD 2.51 Billion
  • CAGR (2024-2030):18.5%
  • North America: Largest market in 2023

Key Companies & Market Share Insights

Key players operating in the quantum computing software market include Microsoft Corporation, IBM Corporation, QC Ware, and Google LLC (Alphabet Inc.).

  • IBM Corporation offers a comprehensive portfolio of quantum software solutions, led by Qiskit, an open-source quantum software development kit (SDK) that supports quantum program development and execution. IBM also provides tools such as Quantum Composer and Quantum Lab, which enable users to design and simulate quantum circuits and advance quantum algorithm research. These solutions, combined with IBM Quantum Experience, deliver cloud-based access to quantum processors and foster experimentation and innovation.
  • QC Ware provides a broad range of quantum computing software solutions, including quantum algorithms, optimization tools, and quantum machine learning applications. Its flagship product, Forge, enables the creation and deployment of quantum algorithms tailored to industrial use cases, supporting advanced simulations and complex problem-solving across multiple sectors.

Key Players

  • 1QBIT
  • Accenture PLC
  • AWS Inc.
  • Cambridge Quantum Computing
  • D-Wave Systems
  • Fujitsu Ltd.
  • Google LLC
  • Honeywell Inc.
  • Huawei Technology Co. Ltd.
  • IBM Corporation
  • Microsoft Corporation
  • QC Ware
  • Rigetti Computing
  • Riverlane
  • Zapata Computing

Explore Horizon Databook – The world's most expansive market intelligence platform developed by Grand View Research.

Conclusion

The quantum computing software market is positioned for strong growth through 2030, driven by increasing demand for industry-specific quantum applications, expanding healthcare and financial use cases, and the rapid evolution of cloud-based quantum platforms. Continued investments in superconducting qubit technologies, quantum machine learning, and cloud deployment models are expected to accelerate adoption and innovation. With North America leading the market and major technology providers expanding their software ecosystems, quantum computing software is set to play a transformative role across industries in the coming years.

Pressure Transmitter Market 2030: Innovations Transforming Industrial Automation

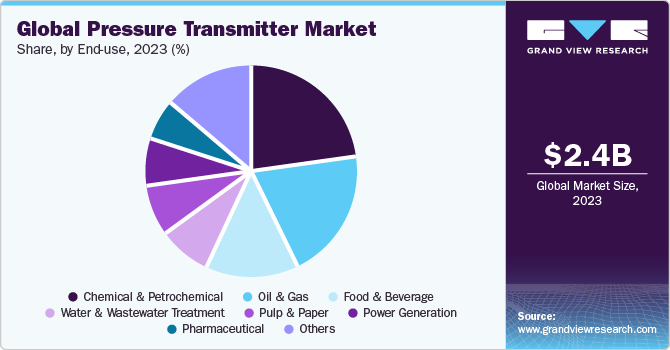
The global pressure transmitter market was valued at USD 2,401.6 million in 2023 and is expected to reach USD 3,132.1 million by 2030, registering a CAGR of 3.9% from 2024 to 2030. Market growth is primarily driven by the rising need for accurate, reliable, and consistent pressure measurement across a wide range of industrial applications.

Pressure transmitters are extensively used in industries such as oil and gas, chemical and petrochemical, and power generation. Growing demand across upstream, midstream, and downstream oil and gas operations—including wellhead pressure monitoring, pipeline surveillance, and refinery processing—is a major factor supporting market expansion.

Global Pressure Transmitter market share and size, 2023

In addition, the increasing adoption of Industry 4.0, along with the shift toward smart factories in the U.S., is contributing to market growth. The introduction of advanced pressure transmitters equipped with features such as wireless communication, digital interfaces, and remote monitoring capabilities is further strengthening demand, particularly in technologically advanced industrial environments.

The need for precise and reliable pressure measurement solutions is also increasing in chemical processing applications. According to the American Chemistry Council, the U.S. chemical industry generated USD 639 billion in revenue in 2022. This industry produces a broad range of products, including plastics, synthetic fibers, fertilizers, pharmaceuticals, and specialty chemicals. High levels of innovation and substantial investments in research and development continue to drive demand for advanced instrumentation, including pressure transmitters. These factors are expected to support sustained market growth over the forecast period.

Order a free sample PDF of the Pressure Transmitter Market Intelligence Study, published by Grand View Research.

Key Market Trends & Insights

  • Asia Pacific accounted for the largest revenue share of 46.9% in 2023. Growth in the region is driven by rapid digitalization and the increasing adoption of the industrial Internet of Things (IIoT), which requires advanced sensors capable of real-time data transmission. Rising industrialization, increasing automation, and significant infrastructure investments further support market expansion. Major manufacturing hubs such as China, Japan, and India play a crucial role in driving regional growth.
  • By Type, the differential-pressure transmitter segment dominated the market with a revenue share of 51.24% in 2023. These transmitters are widely used for measuring flow, level, and pressure differences across various industrial processes. Their ability to withstand mechanical stress, vibrations, and harsh operating conditions makes them well-suited for industrial environments. Availability in multiple configurations and customization options further enhances their adoption.
  • By Sensing Technology, the piezoresistive segment led the market with a revenue share of 46.4% in 2023. Piezoresistive pressure transmitters are valued for their accuracy, durability, and reliability and are widely used in industries such as oil and gas, automotive, aerospace, medical, and chemical processing. Their suitability for harsh environments is expected to drive continued demand.
  • By End Use, the oil and gas segment held the largest revenue share of 20.43% in 2023. Pressure transmitters play a critical role in ensuring safe and efficient operations across oil and gas facilities, including offshore platforms and storage tanks. Increasing emphasis on operational safety and process efficiency continues to support market growth in this segment.
  • By Fluid Type, the liquid segment dominated the market with a revenue share of 70.71% in 2023. Pressure transmitters are widely used to measure pressure in liquids across industries such as chemicals, pharmaceuticals, food and beverage, water and wastewater treatment, and oil and gas. Their ability to handle corrosive and abrasive fluids in both hazardous and non-hazardous environments drives strong adoption.
  • By Application, the pressure measurement segment accounted for the largest revenue share of 49.51% in 2023. These transmitters are designed to deliver high accuracy, fast response times, and reliability. Advanced features such as digital communication protocols, temperature compensation, and self-diagnostics contribute to their widespread use in industrial processes.

Market Size & Forecast

  • 2023 Market Size: USD 2,401.6 Million
  • 2030 Projected Market Size: USD 3,132.1 Million
  • CAGR (2024-2030): 3.9%
  • Asia Pacific: Largest market in 2023

Key Companies & Market Share Insights

The global pressure transmitter market is highly competitive, with the presence of both global and regional manufacturers. Companies are focusing on growth strategies such as mergers and acquisitions, joint ventures, and product innovation. Products are distributed through multiple channels, including distributors, company-owned platforms, retailers, and e-commerce. For example, in November 2022, Emerson launched a new line of Rosemount 3051 pressure transmitters designed to deliver enhanced accuracy and reliability in harsh environments, featuring advanced diagnostics and wireless capabilities for easier installation and maintenance.

Key Players

  • ABB Group
  • Siemens
  • Schneider Electric SE
  • Hitachi, Company limited
  • Honeywell International
  • Yokogawa Electric Corp
  • Emerson Electric Company
  • The Danfoss Group
  • Fuji Electric Co ltd v, Ltd.
  • TE Connectivity Ltd
  • Zemic Group
  • Anfield Sensors Inc
  • Endress+Hauser AG
  • LCM Systems Limited
  • SOR Controls Group

Explore Horizon Databook – The world's most expansive market intelligence platform developed by Grand View Research.

Conclusion

The pressure transmitter market is expected to experience steady growth through 2030, supported by increasing industrial automation, rising demand for precise pressure measurement, and the adoption of smart manufacturing technologies. Strong demand from the oil and gas and chemical industries, combined with advancements in sensing technologies and digital connectivity, will continue to shape market development. Asia Pacific is set to remain the dominant region, while ongoing product innovation and strategic expansions by key players will further strengthen the market’s growth trajectory.

Precision Fermentation Market 2033: Unleashing the Future of Food Production

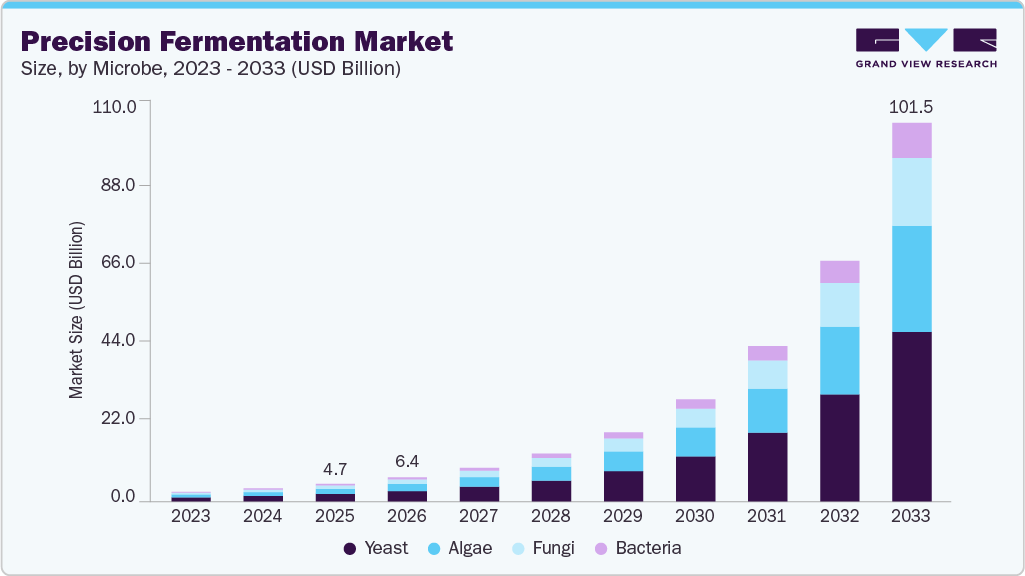
The global precision fermentation market was valued at USD 4.68 billion in 2025 and is expected to grow to USD 101.53 billion by 2033, with a CAGR of 48.3% from 2026 to 2033. This significant growth is largely driven by the increasing demand for sustainable and eco-friendly products. Consumers' growing awareness of the environmental impact of traditional production methods—including deforestation, greenhouse gas emissions, and water pollution—has intensified the shift toward precision fermentation.

There is a rising demand for alternative protein sources due to environmental concerns surrounding traditional methods of protein production. As consumer preferences shift towards plant-based animal proteins, changes in eating habits are occurring. This transition was further accelerated by the beef and pork shortages during the pandemic, which led to a surge in demand for precision fermentation-based products. Increased sales of plant-based products also signal a broader preference for alternative protein sources.

Precision fermentation market size and growth forecast (2023-2033)

Technological advancements, along with growing regulatory support, have played a significant role in driving market expansion. Breakthroughs in biotechnology, combined with heightened environmental concerns and government backing, have spurred the growth of precision fermentation. This method offers the opportunity to produce a variety of sustainable, nutritious, and cost-effective protein sources, which are further driving its demand. The market's expansion reflects its importance in producing sustainable products, alternative protein sources, and specialized ingredients across industries like food, pharmaceuticals, and cosmetics.

In the food industry, advancements in product development have become a key trend. Leading companies in the food and nutrition sector are focusing on innovations to improve their market position. One notable development is the introduction of animal-free ingredients in food products, which is significantly shaping the market.

Order a free sample PDF of the Precision Fermentation Market Intelligence Study, published by Grand View Research.

Key Market Trends & Insights

  • North America dominated the precision fermentation market with the largest revenue share of 40.8% in 2025. This dominance is driven by rising consumer awareness and growing demand for sustainable and eco-friendly products. The increasing adoption of healthy food ingredients and the growing trend of veganism have contributed to this. According to The Hartman Group, approximately 40% of U.S. adults, or over 90 million people, are projected to embrace these products by 2027, with a total potential reach of 132 million consumers.
  • By Microbe, the yeast segment held the largest revenue share of 43.1% in 2025. Yeast’s well-established scalability, regulatory approval, and efficient protein expression make it the preferred choice for industrial applications. Yeast strains like Saccharomyces cerevisiae and Pichia pastoris offer fast fermentation cycles, consistent yields, and compatibility with large-scale bioreactors, making them ideal for producing ingredients like whey and casein proteins, enzymes, and egg white proteins. Additionally, yeast's Generally Recognized As Safe (GRAS) status in key markets reduces regulatory hurdles and shortens time-to-market.
  • By Ingredients, the whey and casein protein segment led with the largest revenue share of 20.8% in 2025. The popularity of precision-fermented whey and casein proteins is driven by their ability to match the amino acid profile, functional performance, and sensory qualities of traditional dairy proteins. These alternatives eliminate animal dependency while significantly reducing environmental impact. They are particularly favored in dairy alternatives and functional nutrition applications due to growing consumer demand for sustainable, lactose-free, and allergen-free products.
  • By End Use, the food & beverages segment accounted for the largest revenue share of 63.1% in 2025. The commercial use of animal-free proteins, enzymes, and flavor-enhancing ingredients in food products has accelerated, thanks to precision fermentation. This method enables the creation of dairy-identical proteins, egg proteins, and other ingredients that integrate seamlessly into food formulations without compromising taste, texture, or nutritional value. Consumer demand for sustainable, clean-label, and allergen-free products has also contributed to the food industry's dominant position.

Market Size & Forecast

  • 2025 Market Size: USD 4.68 Billion
  • 2033 Projected Market Size: USD 101.53 Billion
  • CAGR (2026-2033): 48.3%
  • North America: Largest market in 2025
  • Asia Pacific: Fastest growing market

Key Companies & Market Share Insights

Leading players in the precision fermentation market are expanding their presence and increasing the reach of their products and services. Strategies such as geographical expansion and strategic partnerships are crucial to sustaining market growth.

Key Players

  • Geltor
  • Perday Day Inc
  • The Every Co.
  • Impossible Foods Inc.
  • Motif FoodWorks Inc.
  • Formo
  • Eden Brew
  • Mycorena
  • Change Foods
  • MycoTechnology

Explore Horizon Databook – The world's most expansive market intelligence platform developed by Grand View Research.

Conclusion

The precision fermentation market is poised for substantial growth over the next decade, driven by rising consumer demand for sustainable, eco-friendly alternatives to traditional food production methods. With technological innovations and increased regulatory support, precision fermentation is set to play a pivotal role in meeting the growing global demand for alternative proteins, specialized ingredients, and sustainable food options. North America remains the largest market, while the Asia Pacific region is anticipated to see the fastest growth, further cementing precision fermentation’s place as a key player in global food, pharmaceutical, and cosmetics industries.

Monday, January 5, 2026

Potash Market 2032: The Future of Fertilizer Innovation

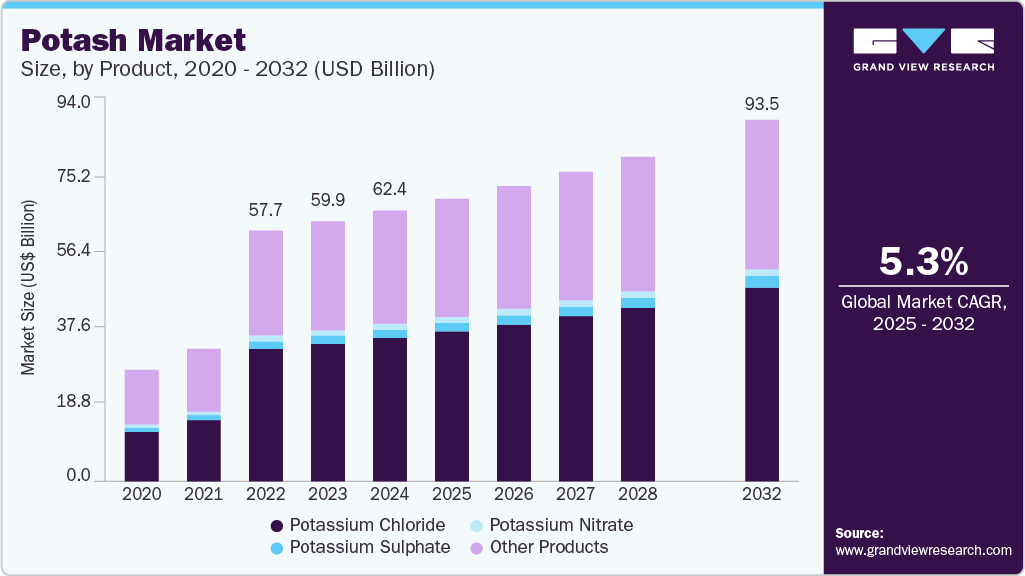
The global potash market was valued at USD 62,374.0 million in 2024 and is projected to reach USD 93,501.2 million by 2032, expanding at a CAGR of 5.3% from 2025 to 2032. Market growth is closely linked to the rising global population, which directly increases demand for food and agricultural products and, in turn, drives the need for higher agricultural productivity.

As population levels continue to grow worldwide, food demand is rising correspondingly. To meet this demand, farmers are increasingly focused on improving crop yields and optimizing agricultural output. Potash plays a vital role in this process by supplying potassium, an essential nutrient that supports root development, nutrient uptake, and overall plant growth. Its use is critical to maintaining soil fertility and ensuring healthy crop production.

Potash market size was valued at USD 62,374.0 million in 2024 and is projected to grow at 5.3% CAGR to reach USD 93,501.2 million by 2032.

The United States represents a strong and stable market for potash, supported by its extensive and diversified agricultural sector. A wide range of crops is cultivated across large areas of farmland, creating sustained demand for essential nutrients such as potash. The consistent requirement for crop productivity, soil health management, adoption of precision agriculture, specialty crop cultivation, technological innovation, and government support collectively contribute to steady potash consumption in the U.S. market. These factors ensure ongoing demand to support agricultural output and food supply needs.

Potash holds a crucial position in global agriculture as a primary source of potassium, a nutrient fundamental to plant health and development. Potassium chloride (KCl) is the most widely used form of potash, accounting for the majority of global consumption. Market growth is primarily driven by the need to increase food production and manage soil fertility as global food demand rises. Potash enhances plant resilience to drought and disease while improving both crop yield and quality. Major consuming regions include Asia Pacific—particularly China and India—Latin America, and North America, where large-scale commercial farming is prevalent.

Order a free sample PDF of the Potash Market Intelligence Study, published by Grand View Research.

Key Market Trends & Insights

  • Regional Outlook: Asia Pacific dominated the global potash market, accounting for more than 38.4% of total revenue in 2024. This leadership is driven by strong demand in major agricultural economies such as China and India, where large populations require substantial food production. In China, potash demand is linked to the cultivation of crops including rice, wheat, corn, and vegetables, while India’s consumption is driven by crops such as rice, wheat, sugarcane, and cotton. Factors such as population growth, urbanization, and increasing emphasis on sustainable farming practices continue to support potash demand in the region.
  • By Product: The potassium chloride segment held the largest market share, accounting for 53.0% of total revenue in 2024. Commonly known as Muriate of Potash (MOP), potassium chloride is widely used as a key component in nitrogen, phosphorus, and potassium (NPK) fertilizers and also serves as a raw material for various industrial applications. Rising global food demand driven by population growth has increased reliance on potash-based fertilizers, with countries such as China and India playing a critical role in shaping global consumption trends.
  • By End Use: The agriculture segment dominated the market, with a revenue share of 93.1% in 2024. This dominance reflects the agricultural sector’s dependence on potash to enhance crop growth, maximize yields, and support global food security. Potash facilitates healthy plant development and is a core component of modern fertilizer formulations. As food demand continues to rise worldwide, farmers are increasingly dependent on potash-based fertilizers to improve productivity, resulting in sustained and robust demand from the agriculture sector.

Market Size & Forecast

  • 2024 Market Size: USD 62,374.0 Million
  • 2032 Projected Market Size: USD 93,501.2 Million
  • CAGR (2025-2032): 5.3%
  • Asia Pacific: Largest market in 2024

Key Companies & Market Share Insights

The potash market includes several prominent global players, including Dow and Linde Plc. Among key participants, K+S Aktiengesellschaft stands out as a major mining and chemical company with operations across Europe, North America, Latin America, Asia Pacific, and the Middle East & Africa. The company operates through its Potash and Magnesium Products and Salt segments, offering fertilizers for agriculture, industrial potash products, and solutions for animal nutrition and pharmaceuticals. With a broad product portfolio that includes potassium chloride, magnesium sulfate, and specialty fertilizers, K+S plays an important role in serving agriculture, food processing, chemical manufacturing, pharmaceutical, and water treatment industries worldwide.

Key Players

  • JSC Belaruskali
  • Compass Minerals Intl. Ltd.
  • Mosaic Company
  • Uralkali
  • Rio Tinto Ltd.
  • BHP Billiton Ltd.
  • Eurochem
  • Red Metal Ltd.
  • Encanto Potash Corp. (EPC)
  • Intrepid Potash Inc,
  • K+S Aktiengesellschaft
  • Nutrien

Explore Horizon Databook – The world's most expansive market intelligence platform developed by Grand View Research.

Conclusion

The global potash market is expected to experience steady growth through 2032, driven by rising population levels, increasing food demand, and the critical role of potassium in agricultural productivity. Strong demand from major agricultural regions, particularly Asia Pacific, along with sustained consumption in North America and Latin America, underpins long-term market stability. While geopolitical factors and supply constraints have introduced volatility, growing adoption of sustainable farming practices and specialty fertilizers presents new opportunities. As global agriculture continues to evolve to meet food security challenges, potash will remain a fundamental input supporting crop yield, quality, and resilience worldwide.

Pork Meat Market 2030: Trends Shaping the Future

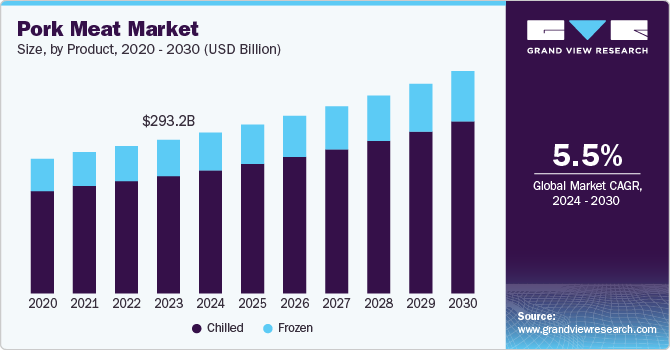
The global pork meat market was valued at USD 293.18 billion in 2023 and is expected to reach USD 424.44 billion by 2030, expanding at a CAGR of 5.5% from 2024 to 2030. Market growth is primarily driven by the increasing global demand for protein-rich foods. Pork, which offers a well-balanced nutritional profile, remains a major source of protein, especially in regions where it is a dietary staple.

As global population levels continue to rise and dietary preferences evolve, consumers are increasingly seeking affordable and widely available protein sources, leading to higher pork consumption worldwide. This trend is particularly prominent in developing economies, where rising income levels and improved living standards have enabled greater access to meat-based diets.

Pork meat market size by region, and growth forecast (2018-2030)

The expansion of the retail sector has significantly contributed to the growth of the pork meat industry. Packaged pork products have gained popularity due to their convenience, catering to consumers who prefer ready-to-eat or easy-to-prepare meal options. The growing presence of supermarkets and hypermarkets has improved the availability of shrink-wrapped and chilled pork products, which help preserve freshness and extend shelf life. This shift toward packaged food reflects broader consumer preferences for convenience and continues to support pork meat sales.

Growing consumer awareness related to health and nutrition is another key factor shaping the market. As individuals become more mindful of their dietary choices, demand for lean and organic meat options has increased. Concerns regarding highly processed foods and their potential health impacts have encouraged consumers to seek cleaner and more natural alternatives. In response, pork producers are increasingly expanding their organic and premium product offerings to address the needs of health-conscious consumers.

Order a free sample PDF of the Pork Meat Market Intelligence Study, published by Grand View Research.

Key Market Trends & Insights

  • Regional Outlook: Asia Pacific accounted for the largest share of the global pork meat market, representing 45.0% of total revenue in 2023. Consumers across the region are increasingly aware of health and nutrition, recognizing pork as a valuable source of protein and essential vitamins. This trend is particularly evident among fitness-focused consumers who favor lean pork cuts for muscle development and overall health. Additionally, the food service industry plays a vital role in driving pork consumption, supported by increased dining out and the popularity of fast-casual restaurants.
  • By Product: The fresh pork segment is projected to grow at a CAGR of 4.9% from 2024 to 2030. Rising consumer preference for fresh, high-quality meat products is a key driver of this segment. Many consumers associate fresh pork with better taste and higher nutritional value compared to frozen alternatives. This preference is particularly strong in regions where culinary traditions emphasize fresh ingredients, supporting increased demand for chilled pork products.
  • By Distribution Channel: Supermarkets and hypermarkets generated the largest revenue in 2023, totaling USD 135.71 billion. These retail formats offer convenience through a one-stop shopping experience, allowing consumers to purchase pork alongside other grocery items. Well-structured meat sections, offering fresh, frozen, and processed pork, enhance the shopping experience and encourage regular consumption as part of household meal planning.

Market Size & Forecast

  • 2023 Market Size: USD 293.18 Billion
  • 2030 Projected Market Size: USD 424.44 Billion
  • CAGR (2024-2030): 5.5%
  • Asia Pacific: Largest market in 2023

Key Companies & Market Share Insights

The global pork meat market comprises several prominent players operating at both national and international levels. These companies utilize strategies such as vertical integration, product innovation, sustainability initiatives, and strategic mergers and acquisitions to remain competitive. By focusing on quality assurance, supply chain efficiency, and evolving consumer preferences, market participants continue to strengthen their positions in an increasingly competitive landscape.

Key Players

  • Smithfield Foods, Inc.
  • Tyson Foods, Inc.
  • JBS S.A.
  • WH Group Limited
  • Hormel Foods Corporation
  • Cargill, Incorporated
  • Marfrig Global Foods S.A.
  • Clemens Food Group
  • BRF S.A. (Sadia)
  • Sysco Corporation
  • Johnsonville LLC
  • Minerva Foods S.A.
  • NH Foods Ltd.

Explore Horizon Databook – The world's most expansive market intelligence platform developed by Grand View Research.

Conclusion

The global pork meat market is positioned for steady growth through 2030, supported by rising demand for protein-rich diets, expanding retail infrastructure, and the growing influence of the food processing and food service industries. Increasing consumer interest in fresh, organic, and lean pork products further enhances market potential. With Asia Pacific leading in consumption and continued innovation across product offerings and distribution channels, the pork meat market is expected to maintain strong momentum, driven by evolving dietary habits and increasing global meat consumption.

Plastic Caps and Closures Market: A Deep Dive into Trends and Innovations

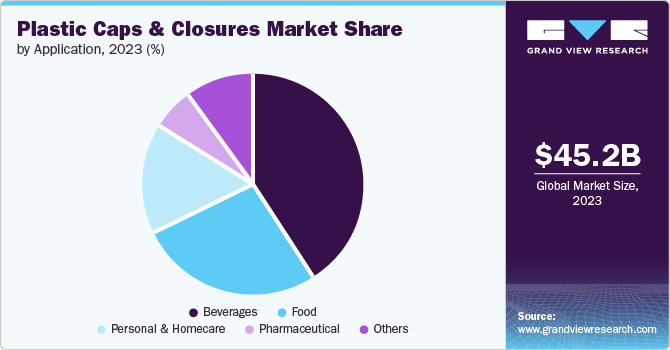
The global plastic caps and closures market was valued at USD 45.22 billion in 2023 and is projected to reach USD 62.45 billion by 2030, growing at a CAGR of 4.8% from 2024 to 2030. Market expansion is largely driven by rising demand from key end-use industries, including food and beverages, pharmaceuticals, and personal care.

Increasing consumer preference for convenient, safe, and hygienic packaging solutions is accelerating the adoption of advanced caps and closures such as tamper-evident (TE) and dispensing closures. Heightened awareness regarding product safety and hygiene—particularly in the post-pandemic environment—has further increased demand for innovative closure systems that protect product integrity and prevent contamination.

Plastic Caps And Closures Market Share by Application, 2023 (%)

The market is also benefiting from growing opportunities related to sustainability. Manufacturers are increasingly focusing on environmentally friendly materials such as polypropylene (PP) and high-density polyethylene (HDPE) to address environmental concerns and comply with evolving regulations. Several companies have launched closures made from post-consumer recycled (PCR) materials to support circular economy initiatives. For instance, leading players such as Berry Global and Aptar have introduced PCR-based closures, reflecting the industry’s shift toward sustainable packaging solutions.

Additionally, the expanding beverage industry, especially in emerging economies within the Asia-Pacific region, continues to fuel demand for plastic caps and closures. In pharmaceutical and personal care applications, the increasing need for precise dispensing, child-resistant features, and secure packaging is creating opportunities for specialized closures that enhance both functionality and user experience.

Order a free sample PDF of the Plastic Caps And Closures Market Intelligence Study, published by Grand View Research.

Key Market Trends & Insights

  • Regional Outlook: Asia Pacific represents the largest and fastest-growing market for plastic caps and closures. Growth in the region is driven by rising consumption of packaged food, beverages, and personal care products, supported by rapid urbanization, higher disposable incomes, and the expansion of modern retail infrastructure. Strong demand from the beverage sector—particularly bottled water and soft drinks—is evident in countries such as India, Indonesia, and Vietnam.
  • By Material: Polypropylene (PP) held the largest market share in 2023 and is expected to remain the fastest-growing material segment through 2030. Its lightweight nature, versatility, cost efficiency, chemical resistance, and recyclability make it a preferred choice for beverage and personal care packaging.
  • By Product: The screw-on caps segment accounted for the largest market share in 2023 due to its widespread use across various industries, particularly in food and beverage packaging. These closures offer ease of use and reliable sealing performance. Meanwhile, specialty closures such as sports caps and child-resistant caps are gaining traction in specific applications, supporting niche market growth.
  • By Technology: The post-mold tamper-evident (TE) band segment dominated the market in 2023 and is projected to be the fastest-growing technology from 2024 to 2030. Demand is driven by the increasing need for secure packaging solutions that prevent tampering and ensure consumer safety, especially in food, beverage, and pharmaceutical products.
  • By Application: The beverages segment held the largest revenue share, exceeding 41% in 2023. Growing consumption of non-alcoholic beverages is expected to sustain segment growth. In addition, the rising popularity of functional beverages—including energy drinks, sports drinks, probiotic beverages, meal replacements, and fruit- and vegetable-based drinks packaged in plastic and glass bottles—is anticipated to further drive demand for plastic closures.

Market Size & Forecast

  • 2023 Market Size: USD 45.22 billion
  • 2030 Projected Market Size: USD 62.45 Billion
  • CAGR (2024-2030):4.8%
  • Asia Pacific: Largest market in 2023

Key Companies & Market Share Insights

The plastic caps and closures market is highly competitive, featuring a mix of multinational corporations, regional manufacturers, and publicly listed companies. Key players primarily serve the food and beverage, pharmaceutical, and personal care industries. Competition is driven by product innovation, sustainability initiatives, and the ability to meet evolving regulatory and consumer requirements.

Key Players

  • Crown
  • Amcor plc
  • Closure Systems International
  • Ball Corporation
  • Silgan Holdings Inc.
  • Berry Global Inc.
  • Guala Closures S.p.A
  • AptarGroup, Inc.
  • BERICAP
  • Nippon Closures Co., Ltd.
  • Sonoco Products Company
  • Webpac Ltd
  • UAB Elmoris
  • CL Smith
  • PELLICONI & C. SPA
  • O. BERK
  • UNITED CAPS

Explore Horizon Databook – The world's most expansive market intelligence platform developed by Grand View Research.

Conclusion

The global plastic caps and closures market is poised for steady growth through 2030, supported by increasing demand for safe, convenient, and sustainable packaging solutions. Expanding beverage consumption, particularly in emerging markets, along with rising requirements for secure and functional closures in pharmaceutical and personal care applications, will continue to drive market expansion. As sustainability becomes a core industry focus, manufacturers investing in recyclable materials, post-consumer recycled content, and advanced tamper-evident technologies are expected to gain a competitive advantage in this evolving market landscape.

Mint Market 2030: Fresh Trends Shaping Tomorrow's Economy

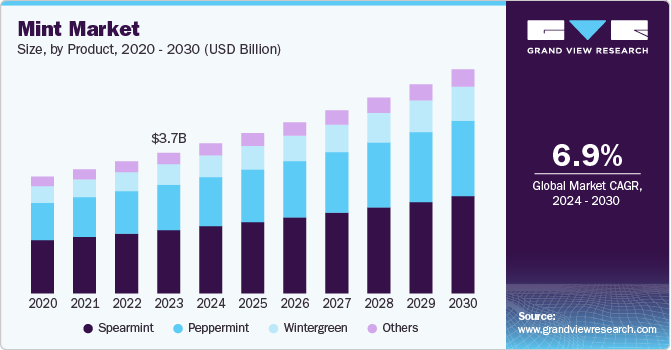
The global mint market was valued at USD 3.72 billion in 2023 and is expected to reach USD 5.94 billion by 2030, registering a CAGR of 6.9% from 2024 to 2030. Market growth, particularly within the peppermint oil segment, is being driven by evolving consumer preferences and ongoing developments across multiple end-use industries.

One of the key factors supporting market expansion is the rising demand for natural and organic ingredients in sectors such as food and beverages, cosmetics, and pharmaceuticals. As consumers become increasingly health-conscious, there is a growing shift away from synthetic additives toward plant-based alternatives. This trend has strengthened the appeal of peppermint oil due to its natural flavor profile and therapeutic properties. In addition, the increasing popularity of aromatherapy has significantly contributed to market growth, as peppermint oil is widely valued for its refreshing scent and potential benefits, including stress reduction and digestive support.

Mint Market Size, by Product, 2020 - 2030 (USD Billion)

The expanding use of peppermint oil in personal care products is another important driver of market growth. Its long shelf life and stability under diverse conditions make it a preferred ingredient in skincare products such as moisturizers and anti-acne formulations. Rising disposable incomes and improving living standards in several regions have also led to increased consumer spending on premium personal care products, further boosting demand. At the same time, the food and beverage industry remains a major contributor to market growth, with mint commonly used as a flavoring agent in confectionery, chewing gum, and beverages.

Advancements in extraction technologies and increased investment in research and development are enabling manufacturers to improve product quality and explore new applications for peppermint oil. The rapid growth of e-commerce platforms has further supported market expansion by improving product accessibility for consumers worldwide. Although challenges such as limited raw material availability and strict quality standards may pose constraints, government initiatives supporting the adoption of natural ingredients are expected to create new growth opportunities. Overall, the mint market is well positioned for sustained growth as it aligns with consumer demand for health, wellness, and sustainability.

Order a free sample PDF of the Mint Market Intelligence Study, published by Grand View Research.

Key Market Trends & Insights

  • Regional Analysis: Asia Pacific emerged as the largest mint market, generating revenue of USD 1.57 billion in 2023, and is projected to grow at a CAGR of 7.3% from 2024 to 2030. Growth in this region is driven by increasing awareness of mint’s health benefits, particularly in countries such as China and India, where mint has a long history of medicinal use. Rising demand for sugar-free and health-oriented confectionery products is also contributing to regional market expansion.
  • By Product: The spearmint segment accounted for the largest market share, with revenue exceeding USD 1.68 billion in 2023. Growth in this segment is supported by increasing consumer awareness of the digestive and respiratory benefits associated with spearmint oil. Demand is further strengthened by its widespread use in pharmaceutical formulations and food products, as well as the growing preference for natural and organic ingredients in personal care and household applications.
  • By Application: The food and beverage segment held the largest market share, generating revenue of USD 1.38 billion in 2023. Mint’s refreshing taste, cooling effect, and versatility have made it a popular ingredient in beverages, candies, and chewing gum. Its ability to refresh the palate and its mild, natural flavor appeal to a broad consumer base, supporting continued growth in this segment.

Market Size & Forecast

  • 2023 Market Size: USD 3.72 Billion
  • 2030 Projected Market Size: USD 5.94 Billion
  • CAGR (2024-2030): 6.9%
  • Asia Pacific: Largest market in 2023

Key Companies & Market Share Insights

The mint market features a competitive landscape with a wide range of participants contributing to industry growth and innovation. Leading companies such as International Flavors & Fragrances Inc. and Young Living Essential Oils are notable for their strong market presence and extensive product portfolios. These firms serve diverse end-use industries, including food and beverages, personal care, and pharmaceuticals, enabling them to maintain a competitive edge in the global market.

Key Players

  • International Flavors & Fragrances, Inc.
  • Young Living Essential Oils
  • doTerra
  • Aksu Vital Natural Products and Cosmetics
  • Aromaaz International
  • Greenleaf Extractions Pvt. Ltd.
  • Lebermuth, Inc.
  • Melaleuca Inc.
  • Mountain Rose Herbs
  • NOW Foods
  • Plant Therapy Essential Oils
  • Kelvin Natural Mint Pvt. Ltd.
  • Rahr Corporation
  • Indesso
  • Lipoid Kosmetic AG
  • Berje, Inc.
  • DSM
  • Hindustan Mint & Agro Products
  • Foodchem International Corporation
  • Vinayak Ingredients (India) Private Limited

Explore Horizon Databook – The world's most expansive market intelligence platform developed by Grand View Research.

Conclusion

The global mint market is expected to witness steady growth through 2030, driven by increasing consumer preference for natural, health-oriented, and sustainable products. Rising demand across food and beverage, personal care, and pharmaceutical applications, combined with technological advancements and expanding e-commerce channels, continues to strengthen market prospects. With Asia Pacific leading in market size and consumption, and ongoing innovation by key industry players, the mint market is well positioned to capitalize on long-term trends centered on wellness, natural ingredients, and evolving consumer lifestyles.