Pages

Tuesday, December 30, 2025

Electric Vehicle Market: Unplugging Trends and Insights

The global electric vehicle (EV) market was valued at USD 1,328.08 billion in 2024 and is expected to expand significantly, reaching USD 6,523.97 billion by 2030. This growth reflects a strong CAGR of 32.5% from 2025 to 2030. Supportive government policies and incentive programs across the globe are playing a critical role in accelerating EV adoption. Many countries have introduced strict emission regulations along with subsidies, tax exemptions, and financial incentives for both manufacturers and consumers, encouraging a transition away from internal combustion engine vehicles toward electric alternatives.
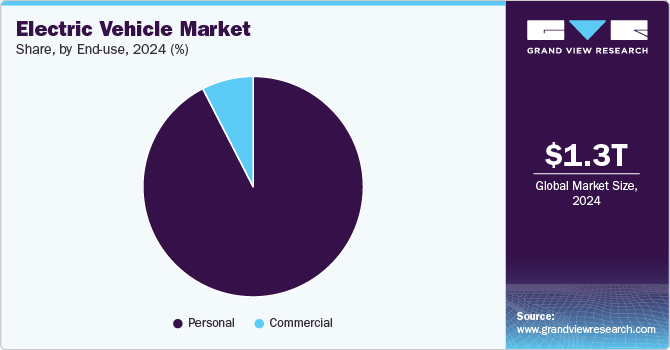
Electric Vehicle Market Share, by End Use, 2024 (%)

Technological progress, particularly in battery innovation, is another major growth driver. Advancements in lithium-ion batteries and the development of solid-state battery technologies are improving vehicle range, performance, and safety while simultaneously reducing costs. These improvements are making EVs more affordable and attractive to a broader consumer base, further accelerating market expansion.

The rapid growth of the transportation and logistics sectors is also contributing to increased EV demand. Rising global trade and the expansion of e-commerce have intensified the need for efficient, cost-effective, and sustainable transportation solutions. Electric vehicles offer lower emissions and reduced operating costs compared to conventional vehicles, making them especially suitable for urban delivery operations where air pollution is a major concern. Logistics providers are increasingly deploying electric vans and trucks to comply with regulations and benefit from lower fuel and maintenance expenses. For example, in May 2024, Amazon introduced 50 heavy-duty electric trucks for freight operations across Southern California, supporting decarbonization efforts across first-, middle-, and last-mile delivery.

Infrastructure development and technological innovation continue to support EV adoption across transportation and logistics. According to the U.S. Department of Energy, more than 10,000 EV charging stations were installed across the U.S., significantly boosting battery electric and plug-in electric vehicle sales. Governments worldwide are investing heavily in charging infrastructure while offering incentives to encourage EV ownership. At the same time, increasing consumer awareness of environmental issues is driving demand for eco-friendly transportation and delivery solutions. Together, regulatory support, infrastructure expansion, and changing consumer attitudes are accelerating the shift toward electric vehicles and reinforcing their importance in the future of mobility and logistics.

Order a free sample PDF of the Electric Vehicle Market Intelligence Study, published by Grand View Research.

Key Market Trends & Insights

  • Asia Pacific: The Asia Pacific region dominated the global EV market in 2024, accounting for a revenue share of 49.2%. Growth in this region is driven by rapid infrastructure development and strong government support. China, Japan, and South Korea are leading contributors, with China emerging as a global leader in EV production and sales due to aggressive electrification policies, subsidies, and strict emission standards. Japan and South Korea continue to focus on technological innovation, particularly in battery efficiency and charging infrastructure. Rising fuel prices and increasing demand for sustainable mobility solutions are further boosting EV adoption across the region.
  • By Vehicle Type – Passenger Cars: Passenger cars represented the largest market share at 89.0% in 2024. The segment is expected to grow rapidly as EV adoption expands across major markets. According to the International Energy Agency (IEA), approximately 10 million electric cars are expected to be sold in China in 2024, accounting for about 45% of total car sales in the country. In the U.S., electric vehicles are projected to represent roughly one out of every nine cars sold.
  • By Propulsion Type – Battery Electric Vehicles (BEVs): BEVs dominated the market in 2024, supported by growing environmental awareness and demand for zero-emission transportation. BEVs offer a cleaner alternative to traditional vehicles and are increasingly adopted in both private and public transport. The rising use of electric buses in urban transit systems has further strengthened BEV demand, prompting manufacturers to introduce new models to meet market needs.
  • By Drive Type – Front-Wheel Drive (FWD): The FWD segment led the market in 2024 due to its cost advantages in vehicle manufacturing. FWD systems require fewer components, reducing production costs and enabling manufacturers to offer more competitively priced vehicles. Additionally, FWD EVs are typically lighter, improving efficiency and lowering operating costs, which appeals to both consumers and automakers.
  • By Vehicle Speed – 100 MPH to 125 MPH: Vehicles with speed capabilities between 100 MPH and 125 MPH accounted for the largest market share in 2024. Demand for high-performance electric cars, along with electric two- and three-wheelers, is driving this segment. Consumers increasingly seek EVs that combine sustainability with strong performance, making this speed range attractive for both city driving and highway use.
  • By Vehicle Class – Low-Price EVs: Low-priced electric vehicles dominated the market in 2024, reflecting growing consumer demand for affordable EV options. Government incentives, technological advancements, and rising environmental awareness have made EVs more accessible, particularly in emerging economies and among cost-conscious buyers seeking alternatives to gasoline-powered vehicles.
  • By End-Use – Personal Segment: The personal EV segment held the largest market share in 2024. Personal electric vehicles appeal to environmentally conscious consumers due to their zero-emission operation. Government subsidies, tax incentives, and supportive policies have significantly encouraged adoption by reducing upfront costs and addressing infrastructure concerns. With governments setting ambitious carbon reduction targets, the demand for personal EVs is expected to continue rising.

Market Size & Forecast

  • 2024 Market Size: USD 1,328.08 Billion
  • 2030 Projected Market Size: USD 6,523.97 Billion
  • CAGR (2025-2030): 32.5%
  • Asia Pacific: Largest market in 2024

Key Companies & Market Share Insights

Leading players in the electric vehicle market include AB Volvo, Volkswagen Group, BYD Company Ltd., and others. Companies are focusing on advanced technologies, product innovation, and strategic partnerships to strengthen their market position. Common strategies include new product launches, geographic expansion, collaborations, and long-term agreements.

  • AB Volvo: AB Volvo is a global manufacturer of commercial vehicles, including trucks, buses, and construction equipment. Operating through segments such as Volvo Trucks, Volvo Construction Equipment, and Volvo Buses, the company emphasizes innovation and sustainability. Volvo has been a pioneer in electric and autonomous vehicle development as part of its commitment to reducing carbon emissions.
  • Volkswagen Group: Volkswagen Group has established itself as a major player in the EV market through its strong focus on sustainable mobility. The introduction of the ID. series, including models such as the ID.3 and ID.4, highlights the company’s commitment to electrification. Significant investments in battery technology, manufacturing facilities, and charging infrastructure support this strategy. Additionally, Volkswagen’s diverse brand portfolio—including Audi, Porsche, and Škoda—continues to expand its electric vehicle offerings to meet rising global demand.

Key Players

  • AB Volvo
  • BYD Company Ltd.
  • Ford Motor Company
  • General Motors
  • Honda Motor Co., Ltd.
  • Kawasaki Motors Corp., U.S.A
  • Mercedes-Benz Group AG
  • Mitsubishi Motors Corporation
  • Nissan Motor Co., Ltd.
  • Renault Group
  • Tesla, Inc.
  • Toyota Motor Corporation
  • Volkswagen Group
  • Zero Motorcycle

Explore Horizon Databook – The world's most expansive market intelligence platform developed by Grand View Research.

Conclusion

The global electric vehicle market is undergoing rapid transformation, supported by strong policy backing, technological innovation, and expanding infrastructure. With market value expected to grow from USD 1,328.08 billion in 2024 to USD 6,523.97 billion by 2030, EVs are becoming a central pillar of sustainable transportation. Asia Pacific remains the dominant region, while passenger cars, battery electric vehicles, and low-priced EVs continue to drive widespread adoption. As governments, manufacturers, and consumers collectively prioritize decarbonization and efficiency, electric vehicles are set to play a defining role in shaping the future of global mobility and logistics.

Diamond Market 2033: The Future of Sparkle and Investment

The global diamond market was valued at USD 42.74 billion in 2025 and is expected to reach USD 53.16 billion by 2033, expanding at a CAGR of 2.7% from 2026 to 2033. Market growth is primarily supported by rising demand for branded and customized jewelry, particularly among millennials and Gen Z consumers, who increasingly seek individuality and personalization in luxury purchases.

Diamond market size and growth forecast (2023-2033)

Another major driver of market expansion is the growing adoption of digital traceability and ethical sourcing practices, which has strengthened consumer trust and accelerated diamond sales worldwide. Sustainability has emerged as a core focus within the modern diamond industry, with both producers and consumers placing greater emphasis on responsible sourcing and environmental protection. Leading mining companies are investing in low-impact extraction methods, renewable energy solutions, and comprehensive mine-to-market traceability systems to reduce environmental impact and enhance transparency. Innovations such as blockchain-enabled tracking, carbon-neutral mining initiatives, recycled diamonds, and eco-certifications are gaining widespread acceptance. These efforts not only lower the industry’s ecological footprint but also support local communities and ecosystems, reinforcing long-term accountability and trust across the supply chain.

Consumer behavior within the diamond market is evolving toward branded, personalized, and story-driven purchases, moving beyond traditional perceptions of luxury. Millennials and Gen Z, in particular, prioritize authenticity, ethical practices, and emotional value, driving strong demand for bespoke engagement rings and customized jewelry designs. At the same time, lab-grown diamonds have entered the mainstream, supported by competitive pricing, sustainability appeal, and physical properties identical to natural diamonds. However, premium natural diamonds continue to appeal to high-net-worth individuals who value rarity and long-term investment potential. This shift in preferences has diversified the market, allowing natural and lab-grown diamonds to coexist as complementary segments within the broader luxury landscape.

Order a free sample PDF of the Diamond Market Intelligence Study, published by Grand View Research.

Key Market Trends & Insights

  • North America: North America accounted for over 51.0% of global diamond market revenue in 2025. The region’s steady growth is driven by strong demand for engagement jewelry, high-end luxury purchases, and the expansion of retail channels, including online and custom jewelry platforms. Consumers increasingly prioritize ethical sourcing, traceability, and certified diamonds, encouraging suppliers to enhance transparency and sustainability efforts. While lab-grown diamonds are gaining traction due to affordability and design flexibility, natural diamonds continue to dominate high-value purchases among affluent consumers.
  • By Type – Natural Diamonds: Natural diamonds held more than 71.0% of global market revenue in 2025. Their dominance is attributed to rarity, intrinsic value, and their long-standing association with luxury and prestige. Major mining countries include Russia, Botswana, Canada, and Australia, with companies such as De Beers and ALROSA leading production. Natural diamonds remain highly preferred for high-value applications, especially bridal jewelry and luxury collections, where authenticity, emotional significance, and investment value are key considerations.
  • By Application – Jewelry & Ornaments: The jewelry and ornaments segment accounted for over 95.0% of global market revenue in 2025, making it the largest application segment. Diamonds are extensively used in engagement rings, necklaces, bracelets, and other luxury accessories, with strong consumer preference for certified and branded stones. Rising disposable incomes in emerging economies such as India and China, along with increasing demand for customized and bespoke jewelry, continue to reinforce the dominance of this segment.

Market Size & Forecast

  • 2025 Market Size: USD 42.74 Billion
  • 2033 Projected Market Size: USD 53.16 Billion
  • CAGR (2026-2033): 2.7%
  • North America: Largest market in 2025
  • Asia Pacific: Fastest growing market

Key Companies & Market Share Insights

Major players in the global diamond market include De Beers Group, ALROSA, Rio Tinto Diamonds, and others.

  • De Beers Group: Founded in 1888, De Beers Group is one of the most influential companies in the global diamond industry, operating across exploration, mining, sorting, trading, and branded retail through De Beers Jewelers and Forevermark. The company emphasizes technological innovation, ethical sourcing, and sustainability initiatives to ensure responsible mining and supply-chain transparency. Its global customer base includes luxury jewelry brands and diamond distributors across North America, Europe, the Middle East, and the Asia Pacific.
  • ALROSA: Established in 1992, ALROSA is Russia’s largest diamond mining company and the world’s leading producer of rough diamonds by volume. The company operates major mining assets in Yakutia and the Arkhangelsk region, utilizing advanced exploration and extraction technologies to support long-term resource sustainability. ALROSA supplies high-quality rough diamonds to global polishing and jewelry markets, serving clients across Belgium, India, China, and the UAE.
  • Rio Tinto Diamonds: As part of the Rio Tinto Group, founded in 1873, Rio Tinto Diamonds is a prominent global producer known for premium mining operations such as Argyle and Diavik. The company is recognized for rare and high-value diamonds, including pink, yellow, and champagne stones, which are in strong demand within the luxury jewelry sector. Rio Tinto integrates sustainable mining practices, digital traceability, and transparent supply chains to enhance consumer confidence in ethically sourced natural diamonds.

Key Players

  • ALROSA
  • Anglo American plc.
  • Debswana Diamond Company Ltd.
  • De Beers Group
  • Dominion Diamond Corporation
  • Gem Diamonds
  • Lucara Diamond Corporation
  • Petra Diamonds
  • Rio Tinto Diamonds
  • Rockwell Diamonds

Explore Horizon Databook – The world's most expansive market intelligence platform developed by Grand View Research.

Conclusion

The global diamond market is set to experience steady growth through 2033, driven by evolving consumer preferences, increasing demand for branded and customized jewelry, and a strong emphasis on ethical sourcing and sustainability. While natural diamonds continue to dominate high-value and luxury segments, lab-grown diamonds are expanding the market by appealing to cost-conscious and environmentally aware consumers. North America remains the largest market, supported by mature retail infrastructure and high consumer spending, while Asia Pacific is expected to register the fastest growth due to rising incomes and expanding jewelry demand. Together, innovation, sustainability, and diversification of offerings will continue to shape the long-term outlook of the global diamond industry.

Dental Caries Detectors Market: Unveiling Innovations in Early Detection

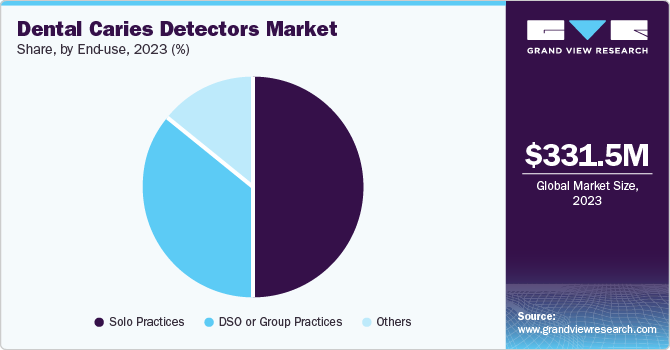
The global dental caries detectors market was valued at USD 331.5 million in 2023 and is projected to reach USD 532.4 million by 2030, growing at a CAGR of 6.7% from 2024 to 2030. These devices play a crucial role in early detection of dental issues, such as cavities, enabling dentists to develop effective treatment plans.

The rising geriatric population and an increasing demand for dental care are major factors driving the growth of the dental caries detector market. Additionally, various government initiatives aimed at improving public oral health are further contributing to the demand for these detection tools.

Dental Caries Detectors Market Share, by End Use, 2023 (%)

Advancements in dental caries detection technologies are also boosting market growth. For example, light-based diagnostic aids, such as digital trans-illumination, light-induced fluorescence, and laser-induced fluorescence, are transforming the way dental issues are detected. These technologies make dental treatments more precise, less invasive, and more comfortable, improving both patient outcomes and overall convenience.

The primary causes of dental caries include plaque buildup, bacterial formation, poor oral hygiene, and certain medical conditions like uncontrolled diabetes. Other contributing factors include lifestyle choices related to urbanization, such as high tobacco and alcohol consumption, poor diet, and excessive sugar intake.

Order a free sample PDF of the Dental Caries Detectors Market Intelligence Study, published by Grand View Research.

Key Market Trends & Insights

  • North America: In 2023, North America dominated the dental caries detectors market, holding a 38.2% revenue share. The region benefits from a well-established dental infrastructure, state-of-the-art dental clinics, and highly educated consumers who prioritize preventive care. The large geriatric population and favorable reimbursement policies further support the demand for dental caries detectors. Additionally, major dental device manufacturers in North America contribute to technological advancements that help drive market growth in the region.
  • Laser Fluorescent Caries Detectors: The laser fluorescence segment led the market in 2023 with a revenue share of 52.1%. This technology aids in the early detection of tooth decay, offering high accuracy and wide acceptance in dental practices. Laser fluorescence is also a continuously evolving technology, offering reliability and patient-friendly benefits.
  • Solo Practices: The solo practices segment accounted for the largest share of the market in 2023. This can be attributed to the increasing number of dentists working in solo practices worldwide. These practices rely on caries detectors for early detection, which helps in diagnosing cavities more accurately and developing effective treatment plans.

Market Size & Forecast

  • 2023 Market Size: USD 331.5 Million
  • 2030 Projected Market Size: USD 532.4 Million
  • CAGR (2024-2030): 6.7%
  • North America: Largest market in 2023
  • Asia Pacific: Fastest growing market

Key Companies & Market Share Insights

Leading companies in the dental caries detector market include KaVo Dental, Quantum Dental Technologies, Acteon, Dentsply Sirona, and Hu-Friedy Mfg. Co., LLC. To stay competitive in the rapidly evolving market, these companies are focusing on strategies such as product innovation, improved research and development, and the expansion of product portfolios.

  • KaVo Dental: KaVo offers advanced products like the KaVo DIAGNOdent Pen and KaVo DIAGNOcam Vision Full HD, both of which are key dental caries detectors.
  • Quantum Dental Technologies: Quantum's Canary System provides an advanced, painless, and non-invasive caries detection solution that enables early detection of dental caries.

Key Players

  • KaVo Dental
  • Quantum Dental Technologies
  • Acteon
  • Centrix, Inc.
  • Kuraray Europe GmbH
  • Dentsply Sirona
  • Hu-Friedy Mfg. Co., LLC.
  • AdDent, Inc.
  • DentLight Inc.
  • Air Techniques, Inc.
  • Ross Video LTD.

Explore Horizon Databook – The world's most expansive market intelligence platform developed by Grand View Research.

Conclusion

The dental caries detector market is poised for substantial growth, driven by advancements in technology, an increasing focus on preventive dental care, and growing demand from both developed and developing markets. With the expanding geriatric population and a rising awareness of oral health, the demand for early cavity detection tools is set to continue its upward trajectory. North America remains the largest market, while Asia Pacific is expected to witness the fastest growth. Leading companies are actively innovating to meet the demand for more accurate, patient-friendly detection methods, further propelling the market forward.

Monday, December 29, 2025

Customer Engagement Solutions Market: Unpacking the Trends for 2026

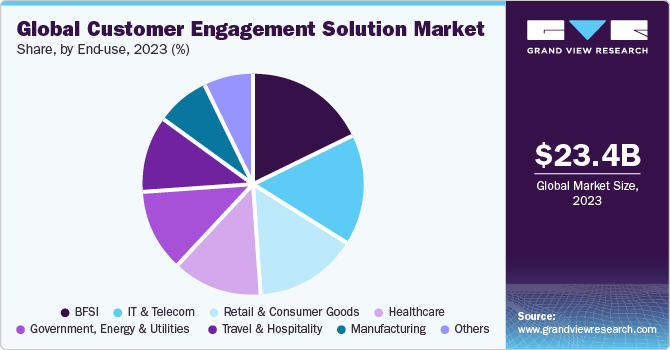
The global customer engagement solutions market was valued at USD 23.45 billion in 2023 and is expected to expand to USD 50.03 billion by 2030, registering a CAGR of 11.8% from 2024 to 2030. This growth is primarily driven by the rising need for personalized and consistent customer experiences across multiple industries.

The increasing adoption of customer engagement solutions to minimize customer churn, along with the rapid expansion of e-commerce and m-commerce platforms, is further accelerating market growth. Additionally, organizations are placing greater emphasis on enhancing customer interactions through omnichannel engagement strategies, which continues to boost demand for these solutions.

Global Customer Engagement Solutions Market share and size, 2023

Technological advancements play a crucial role in driving market expansion. Innovations such as advanced analytics, artificial intelligence (AI), and machine learning (ML) allow organizations to capture, process, and utilize customer data in real time. As a result, businesses can deploy sophisticated customer engagement tools that deliver highly personalized experiences, leading to improved customer satisfaction and stronger brand loyalty.

As the volume and complexity of customer data continue to grow, organizations increasingly rely on data-driven decision-making. Customer engagement solutions offer robust analytics capabilities that enable businesses to collect, analyze, and interpret customer data to derive actionable insights. These insights support better strategic decisions, optimized marketing efforts, and enhanced customer engagement, further contributing to market growth.

Order a free sample PDF of the Customer Engagement Solutions Market Intelligence Study, published by Grand View Research.

Key Market Trends & Insights

  • Regional Insights: North America accounted for the largest market share of 38.2% in 2023 and is expected to witness substantial growth throughout the forecast period. This growth is attributed to the region’s strong data-driven business environment, where organizations increasingly leverage customer insights and analytics to guide decision-making and strategic planning.
  • By Component: The solution segment dominated the market with a revenue share of 67.8% in 2023. The widespread adoption of smartphones and tablets has raised customer expectations for seamless mobile experiences. Consequently, demand for mobile-optimized customer engagement platforms, mobile applications, and responsive websites has increased, supporting market growth.
  • By Deployment: The hosted segment held the largest revenue share in 2023. These solutions support multiple communication channels, including email, social media, chat, and voice, allowing businesses to interact with customers through their preferred platforms and enhance overall engagement and satisfaction.
  • By Enterprise Size: Large enterprises accounted for the highest revenue share in 2023 due to their extensive customer data volumes and strict security and compliance requirements. Customer engagement solutions that prioritize data privacy, security, and regulatory compliance are critical for large organizations to maintain customer trust and mitigate legal risks.
  • By End-Use: The BFSI segment led the market in 2023, driven by growing demand for personalized financial services such as customized banking recommendations, targeted insurance offerings, and proactive financial advice. For example, in June 2023, India-based B2B SaaS startup Nuclei partnered with Oracle to offer its merchant marketplace program and SaaS solutions on Oracle’s digital banking platform, aiming to enhance customer engagement and retention through digital channels.

Market Size & Forecast

  • 2023 Market Size: USD 23.45 billion
  • 2030 Projected Market Size: USD 50.03 billion
  • CAGR (2024-2030): 11.8%
  • North America: Largest market in 2023

Key Companies & Market Share Insights

Prominent players in the customer engagement solutions market include Oracle Corporation and Salesforce.com Inc.

  • Oracle Corporation offers Oracle Retail Customer Engagement Cloud Services, which include customer management and segmentation, loyalty and awards management, and data integration with interactive marketing tools. These features help consolidate customer data, create targeted customer segments, and enable personalized engagement strategies.
  • Salesforce.com Inc. delivers customer engagement solutions through its Experience Cloud platform, which helps organizations create connected digital experiences and enhance overall customer interactions.

Key Players

  • Alvaria, Inc.
  • Avaya Inc.
  • Calabrio Inc.
  • Genesys
  • IBM Corporation
  • NICE
  • Nuance Communications Inc.
  • OpenText Corporation
  • Oracle Corporation
  • Pegasystems Inc.
  • Salesforce.com Inc.
  • SAP SE
  • Verint Systems Inc.

Explore Horizon Databook – The world's most expansive market intelligence platform developed by Grand View Research.

Conclusion

The customer engagement solutions market is poised for robust growth, driven by increasing demand for personalized customer experiences, rapid digital transformation, and advancements in AI and analytics. As organizations continue to prioritize data-driven strategies, omnichannel engagement, and customer retention, the adoption of advanced engagement platforms will accelerate across industries. With strong regional leadership from North America, rising adoption among large enterprises, and significant demand from the BFSI sector, the market is well-positioned to achieve sustained expansion through 2030.

Chemical Injection Skids Market: Rising Demand and Future Trends

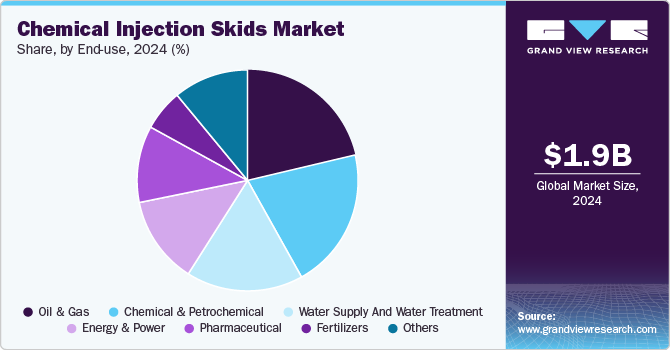
The global chemical injection skids market was valued at USD 1,907.8 million in 2024 and is projected to reach USD 2,375.0 million by 2030, registering a CAGR of 3.8% from 2025 to 2030. Market growth is being supported by rising demand for safe, accurate, and efficient chemical handling solutions across multiple industries, including oil and gas, water treatment, and pharmaceuticals.

Chemical Injection Skids Market Share, By End-Use, 2024 (%)

As organizations focus on improving operational efficiency while complying with increasingly stringent environmental and safety regulations, the adoption of automated chemical injection systems is gaining momentum. These systems enhance dosing accuracy and significantly reduce the likelihood of chemical spills and leakages, making them an attractive solution for operators seeking to improve process reliability and workplace safety.

Technological progress in chemical injection skid design is further accelerating market expansion. The integration of Internet of Things (IoT) technologies and remote monitoring capabilities enables real-time performance tracking, data-driven decision-making, and remote system management. These features help minimize downtime, optimize chemical usage, and enhance overall operational efficiency. With industries placing greater emphasis on sustainability, automation, and safety, demand for advanced chemical injection skids is expected to continue growing as part of the broader shift toward smart industrial solutions.

Order a free sample PDF of the Chemical Injection Skids Market Intelligence Study, published by Grand View Research.

Key Market Trends & Insights

  • Regional Insights: Asia Pacific accounted for 35.3% of the global chemical injection skids market in 2024. Rapid industrialization and rising infrastructure investments across the region are key drivers of this growth. The oil and gas sector in countries such as Indonesia and Malaysia plays a significant role, with chemical injection skids widely used in offshore drilling operations to optimize chemical dosing, improve production efficiency, and manage corrosion.
  • Function Insights: The corrosion inhibition segment dominated the market in 2024, capturing a revenue share of 28.6%. Growing concerns related to equipment degradation and infrastructure protection in industries such as oil and gas, power generation, and water treatment are driving demand for corrosion inhibitors. Incorporating corrosion inhibitors into chemical injection skids allows for precise dosing and continuous monitoring, which helps extend asset lifespan and reduce maintenance costs.
  • End-Use Insights: The oil and gas sector led the market by end use, accounting for 21.5% of total revenue in 2024. Demand from this sector is fueled by the need for effective chemical management solutions to maintain operational integrity under harsh environmental conditions and aging infrastructure. Automated chemical injection skids enable accurate delivery of chemicals such as corrosion inhibitors, biocides, and demulsifiers, ensuring regulatory compliance and operational efficiency.

Market Size & Forecast

  • 2024 Market Size: USD 1,907.8 Million
  • 2030 Projected Market Size: USD 2,375.0 Million
  • CAGR (2025-2030): 3.8%
  • Asia Pacific: Largest market in 2024

Key Companies & Market Share Insights

The chemical injection skids market features a mix of established and emerging players focused on innovation, customization, and strategic expansion. Leading companies such as SPX FLOW Inc. and IDEX Corporation continue to strengthen their market positions through advanced product offerings and global reach.

  • SPX FLOW Inc., headquartered in Charlotte, North Carolina, is a global provider of engineered process solutions serving industries including food and beverage, energy, and industrial manufacturing. The company offers a broad portfolio of high-performance equipment, including pumps, valves, mixers, and process systems, designed to improve operational efficiency and reliability.
  • IDEX Corporation, based in Lake Forest, Illinois, is a diversified global manufacturer known for its innovative fluid handling and metering solutions. Serving sectors such as industrial manufacturing, health and wellness, and fire and safety, IDEX emphasizes product quality, reliability, and continuous investment in research and development to maintain its competitive advantage.

Emerging players such as Dencil Fluidtek Systems Pvt. Ltd. and Petrak Industries Inc. are also gaining traction by offering specialized and customized chemical injection solutions. Dencil Fluidtek, headquartered in Pune, India, focuses on fluid management systems for oil and gas, petrochemical, and water treatment applications, while U.S.-based Petrak Industries specializes in high-performance chemical injection skids and control systems for energy and industrial markets.

Key Players

  • Milton Roy Company
  • AES Arabia Ltd.
  • Petronash
  • Lewa GmbH
  • SPX FLOW Inc.
  • INTECH
  • Integrated Flow Solutions LLC
  • Petroserve International
  • Carotek Inc.
  • IDEX Corporation

Explore Horizon Databook – The world's most expansive market intelligence platform developed by Grand View Research.

Conclusion

The global chemical injection skids market is expected to experience steady growth through 2030, driven by increasing demand for automated, precise, and safe chemical handling solutions. Rising investments in industrial infrastructure, advancements in smart monitoring technologies, and strong demand from the oil and gas sector are key factors supporting market expansion. With Asia Pacific leading regional growth and continued innovation by both established and emerging players, chemical injection skids are set to remain a critical component of modern industrial operations.

Blockchain in Gaming Market: Unlocking the Future of Play

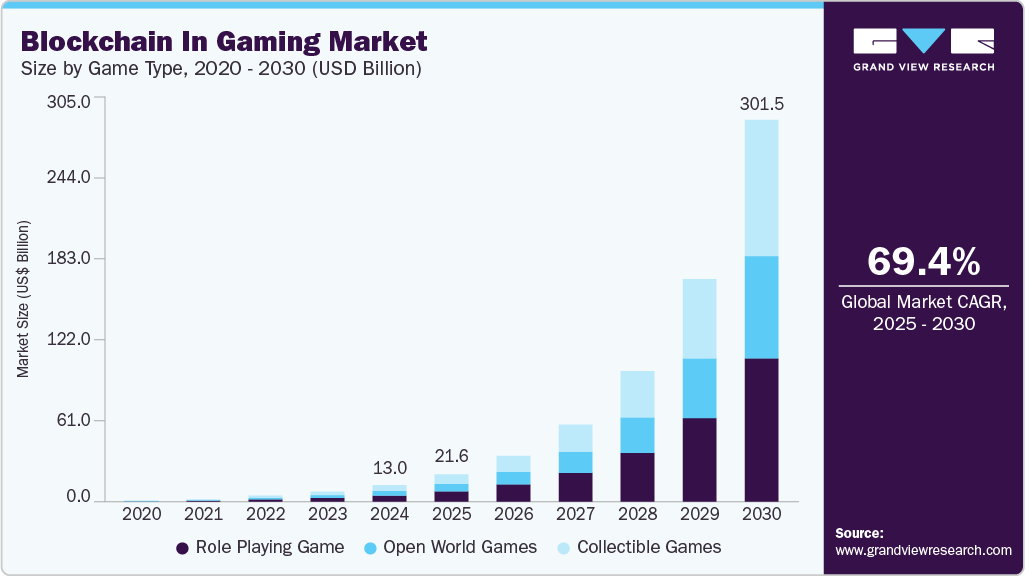
The global blockchain in gaming market was valued at USD 13.0 billion in 2024 and is forecast to reach USD 301.53 billion by 2030, expanding at a remarkable CAGR of 69.4% from 2025 to 2030. This rapid growth is largely driven by the increasing demand for a secure, transparent, and decentralized gaming ecosystem.

Blockchain technology functions as a decentralized and distributed digital ledger that ensures secure transactions and reliable recordkeeping. Its integration into the gaming industry has transformed the way developers and players interact with digital content, enabling the use of cryptocurrencies and non-fungible tokens (NFTs) for purchasing, trading, and owning in-game assets. For example, Axie Infinity is an NFT-based blockchain game with millions of players worldwide who conduct in-game transactions using Ethereum-based cryptocurrencies. By maintaining a public ledger of all transactions, blockchain enhances transparency within the gaming ecosystem, allowing players to verify asset ownership and track transfers. This structure ensures fair gameplay while enabling players to retain true ownership of their digital assets and conduct secure transactions without relying on intermediaries.

Blockchain in gaming market size and growth forecast in USD billion with CAGR (2025-2030)

In recent years, the blockchain gaming sector has experienced a surge in investments and funding. This trend is supported by the growing adoption of blockchain technology, rising interest in decentralized gaming platforms, and the opportunity to deliver innovative gaming experiences along with new monetization models. Increased venture capital and institutional investments indicate rising market maturity and long-term confidence in blockchain gaming. Major gaming studios and technology companies are actively launching blockchain-based titles or investing in Web3 gaming startups, many of which are securing multi-million-dollar funding rounds, further accelerating market growth.

The integration of artificial intelligence (AI) and machine learning (ML) technologies has further strengthened blockchain gaming platforms. These technologies help identify and prevent fraudulent activities, such as bot usage and fake accounts. Additionally, AI and ML are used to analyze player behavior and preferences, enabling personalized gaming experiences through tailored game recommendations and in-game rewards. Game developers also leverage AI-driven insights from player data and feedback to refine game design and improve overall user engagement.

Order a free sample PDF of the Blockchain in Gaming Market Intelligence Study, published by Grand View Research.

Key Market Trends & Insights

  • Regional Insights: Asia Pacific held the largest revenue share of 26.35% in 2024 and is expected to grow at a CAGR of 70.5% over the forecast period. This growth is driven by strong interest in cryptocurrencies, along with high internet and mobile penetration across the region. Increasing participation in digital asset markets has created a favorable environment for blockchain-based gaming platforms.
  • Game Type Insights: The role-playing game (RPG) segment dominated the market in 2024, accounting for 37.1% of total revenue. RPGs offer immersive gameplay, detailed storylines, character development, and expansive virtual worlds, encouraging long-term player engagement and investment of time and resources.
  • Platform Insights: The Ethereum (ETH) segment held the largest revenue share in 2024, supported by its advanced smart contract capabilities. These features allow developers to build decentralized applications (dApps), store in-game assets on the blockchain, and create decentralized marketplaces. Smart contracts also automate game rules, ensuring fairness and transparency in gameplay.
  • Device Insights: The web-based segment led the market in 2024 due to its ease of access and user-friendly experience. Web-based blockchain games can be played directly through browsers without the need for downloads or installations, lowering technical barriers and encouraging broader adoption.

Market Size & Forecast

  • 2024 Market Size: USD 13.0 Billion
  • 2030 Projected Market Size: USD 301.53 Billion
  • CAGR (2025-2030): 69.4%
  • Asia Pacific: Largest market in 2024

Key Companies & Market Share Insights

Prominent companies operating in the blockchain gaming market include Animoca Brands Corporation Limited, Sky Mavis, and Dapper Labs, Inc. Blockchain game developers are increasingly creating interoperable gaming ecosystems, allowing players to use assets across multiple games and platforms. The rise of NFT marketplaces has further enabled players to buy, sell, and trade in-game assets, creating secondary markets and additional revenue streams for developers.

  • Animoca Brands, headquartered in Hong Kong, is a leading player in blockchain gaming and digital entertainment, with operations across North America, Europe, Asia, Australia, and South America. The company has developed and invested in a wide range of Web3 projects, including The Sandbox, Moca Network, Anichess, Open Campus, GAMEE, TinyTap, Phantom Galaxies, and Crazy Defense Heroes.
  • Sky Mavis, based in Singapore, specializes in decentralized applications and is best known for developing Axie Infinity, a blockchain-based game that enables players to own digital assets and earn rewards through gameplay.

Key Players

  • Dapper Labs, Inc.
  • Sky Mavis
  • Splinterlands
  • Animoca Brands Corporation Limited
  • Immutable
  • Uplandme, Inc.
  • Illuvium
  • Mythical Inc.
  • ROKO GAME STUDIOS
  • Autonomous Worlds Ltd.

Explore Horizon Databook – The world's most expansive market intelligence platform developed by Grand View Research.

Conclusion

The global blockchain in gaming market is set for exceptional growth through 2030, driven by increasing demand for decentralized, transparent, and player-owned gaming ecosystems. Advancements in blockchain technology, rising investments, integration of AI and ML, and growing interest in NFTs and cryptocurrencies are reshaping the gaming industry. While regulatory challenges persist, strong growth in Asia Pacific, expanding use of Ethereum-based platforms, and continuous innovation by leading companies position blockchain gaming as a transformative force in the future of interactive entertainment.

Biomethane Market 2030: Powering a Greener Future

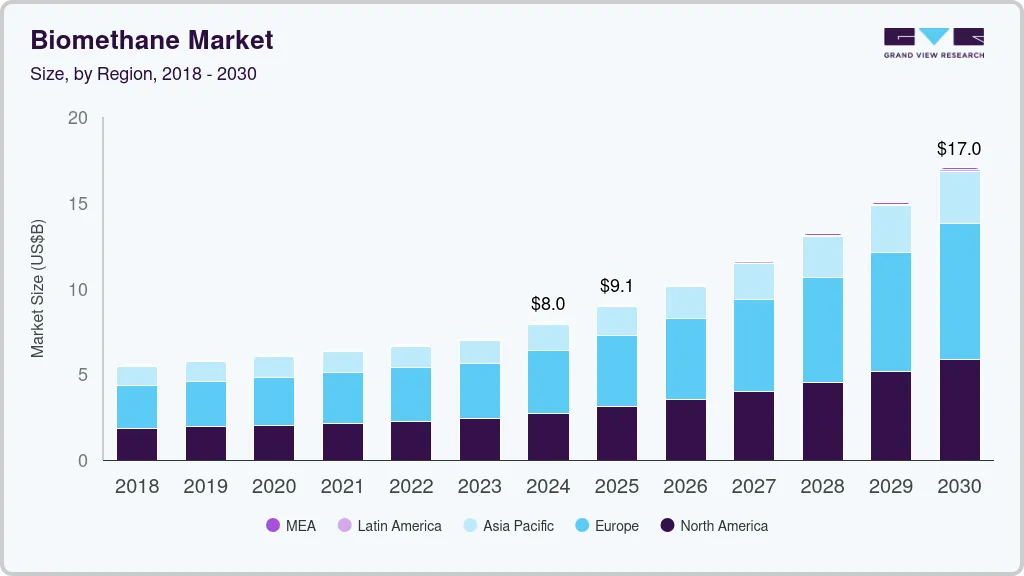
The global biomethane market was valued at USD 7,994.9 million in 2024 and is expected to reach USD 17,031.9 million by 2030, expanding at a CAGR of 13.5% from 2025 to 2030. Biomethane is a renewable energy source with a wide range of applications, including construction, power generation, transportation, and various industrial uses.

Biomethane market size by region, and growth forecast (2025-2030)

The increasing demand for efficient and sustainable power transmission solutions is anticipated to drive market growth during the forecast period. Biomethane is produced from the biological decomposition of organic materials such as agricultural residues, food waste, sewage sludge, and other biodegradable feedstocks. As a renewable and low-carbon energy source, it is widely regarded as a viable alternative to conventional fossil fuels. The production of biomethane is based on anaerobic digestion, a renewable process in which microorganisms break down organic matter in the absence of oxygen to generate biogas, which is subsequently upgraded to biomethane.

Key Market Trends & Insights

  • Regional Insights: Europe led the global biomethane market in 2024, accounting for more than 45.6% of total revenue. This dominance is expected to continue throughout the forecast period due to the increasing availability of biomethane feedstocks and a strong regional focus on alternative and renewable energy sources. Additionally, European universities and research institutions are actively conducting advanced research aimed at reducing technology costs, supported by grants and funding provided by the European Commission for research and development initiatives.
  • Source Insights: Municipal waste emerged as the largest source segment in 2024, contributing approximately 39.0% of total revenue, and is projected to record the fastest CAGR of 14.7% over the forecast period. Rising urbanization and the growing need for sustainable waste management solutions are key drivers for this segment. Organic fractions of municipal solid waste, including food waste, garden residues, and biodegradable packaging, are processed through anaerobic digestion to produce biogas, which is then upgraded to biomethane. This process helps reduce landfill dependence and methane emissions while supporting circular economy objectives by converting waste into renewable energy.
  • End-Use Insights: The construction sector accounted for the largest end-use share, generating over 43.0% of total revenue in 2024. According to the International Energy Agency (IEA), bioenergy contributed approximately 10% of global primary energy demand in 2023, with a significant portion utilized in the form of biogas, including biomethane. Within the construction industry, biomethane is primarily used for heating and cooking purposes, and a substantial share is also injected into gas networks for use as a transportation fuel.

Order a free sample PDF of the Biomethane Market Intelligence Study, published by Grand View Research.

Market Size & Forecast

  • 2024 Market Size: USD 7,994.9 Million
  • 2030 Projected Market Size: USD 17,031.9 Million
  • CAGR (2025-2030): 13.5%
  • Europe: Largest market in 2024

Key Companies & Market Share Insights

Leading companies operating in the biomethane market are implementing various strategies to enhance their market presence and expand their product and service offerings. Key initiatives include capacity expansions, strategic partnerships, and collaborations, all of which are playing an important role in accelerating overall market growth.

Key Players

  • Air Liquide
  • Engie
  • Nature Energy Biogas A/S
  • Gasum
  • Terega Solutions
  • Waga Energy
  • TotalEnergies
  • Chevron
  • Kinder Morgan
  • Archea Energy
  • Envitec Biogas AG
  • Future Biogas Ltd.
  • E.ON SE
  • Verbio Vereinigte Bioenergie AG
  • South Hills RNG

Explore Horizon Databook – The world's most expansive market intelligence platform developed by Grand View Research.

Conclusion

The global biomethane market is poised for robust growth through 2030, driven by rising demand for renewable energy, increasing urban waste generation, and supportive government policies promoting sustainable energy solutions. Europe’s leadership, coupled with advancements in waste-to-energy technologies and expanding applications across construction, transportation, and power generation, positions biomethane as a key contributor to the global energy transition over the forecast period.

Barley Market 2030: Trends Shaping the Future of Grain

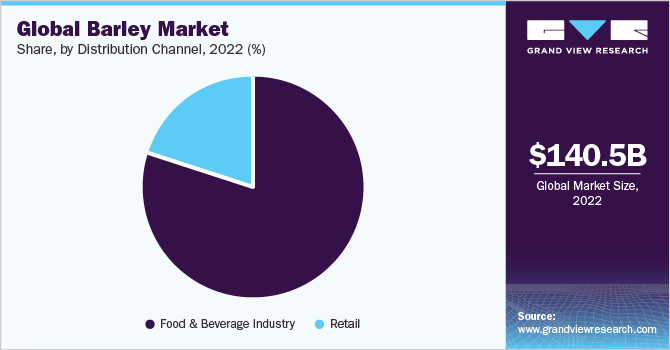
The global barley market was valued at USD 140.45 billion in 2022 and is projected to reach USD 175.8 billion by 2030, expanding at a CAGR of 2.9% between 2023 and 2030. Market growth is largely supported by the increasing use of barley in the brewing and distilling industries, along with rising demand for malted barley across a wide range of food and beverage applications.

Global barley market share and size, 2022

Growing consumption of alcoholic beverages, particularly craft beer and premium spirits, is a key factor contributing to market expansion. This trend has significantly increased the demand for barley within the food and beverage sector. In addition to its role in beverage production, barley remains a critical component of livestock feed. It is widely used in animal feed formulations for poultry, pigs, and cattle. Rising consumption of meat and dairy products—especially in developing economies driven by population growth and increasing income levels—has further strengthened demand for barley as a feed grain. According to the USDA, nearly 70% of globally traded barley is utilized by the feed industry, while a comparatively smaller share is consumed as human food. In this context, Switzerland-based Syngenta has introduced a hybrid feed barley variety, Colossus, in the UK market, designed to improve grain performance.

Barley offers a well-balanced nutritional profile due to its combination of starch and protein, making it a preferred ingredient in animal diets. It provides both energy and protein required to support livestock growth, milk production, and overall animal health. Its relatively high energy density enables efficient feed utilization, thereby improving animal productivity. Moreover, barley’s ability to adapt to a wide range of pedo-climatic conditions enhances its appeal as a feed crop, allowing cultivation in regions where other cereal grains may be less viable and ensuring consistent feed grain availability.

Order a free sample PDF of the Barley Market Intelligence Study, published by Grand View Research.

Key Market Trends & Insights

  • Regional Insights: Europe accounted for the largest share of the global barley market in 2022, capturing 59.9% of total revenue. The growing popularity of craft beer and artisanal spirits across the region has supported this dominance. The increasing number of microbreweries, brewpubs, and small-scale distilleries has driven strong demand for high-quality barley to support specialty beverage production.
  • Type Insights: The malted barley segment led the market in 2022, holding a revenue share of 56.3%. The expansion of artisanal and craft beverage production has significantly boosted demand for malted barley, which enhances flavor and texture in beverages such as beer and whiskey. In March 2021, Southern Health Foods Pvt Ltd launched a malted food drink fortified with essential vitamins and minerals, highlighting the growing application of malted barley beyond alcoholic beverages.
  • Application Insights: The beverage segment dominated the market by application, accounting for 50.4% of total revenue in 2022. Barley producers are increasingly adopting advanced breeding techniques and innovative technologies, including hybrid barley varieties, improved malting characteristics, and genomic tools, to meet beverage industry requirements. Hybrid varieties developed through controlled crossbreeding offer improved yields, enhanced disease resistance, and greater tolerance to environmental stress, contributing to higher barley availability. In December 2022, Brazil-based beer brand Petra introduced Petra Milk, a barley-based milk beverage.
  • Distribution Channel Insights: The food and beverage distribution channel held the largest revenue share of 79.6% in 2022. The rising adoption of plant-based and vegetarian diets has increased demand for barley-based food products. Barley is widely used in plant-based protein bowls, grain salads, veggie burgers, and other meat alternatives due to its nutritional value, texture, and versatility.

Market Size & Forecast

  • 2022 Market Size: USD 140.45 Billion
  • 2030 Projected Market Size: USD 175.8 Billion
  • CAGR (2023-2030): 2.9%
  • Europe: Largest market in 2022

Key Companies & Market Share Insights

The global barley market is highly competitive, with numerous players focusing on product innovation to address evolving consumer preferences. Companies are increasingly introducing sustainable and value-added barley-based products. For instance, in May 2022, Muntons Plc announced the use of 100% environmentally sustainable malt derived from British barley and wheat to support the development of plant-based products such as burgers, sausages, and sliced deli-style alternatives.

Key Players

  • Soufflet Group
  • GrainCorp Limited
  • Cargill
  • Boortmalt Group
  • Malteurop Groupe
  • Crisp Malting Group
  • Muntons Plc
  • Maltexco S.A.
  • Grain Millers Inc
  • Malt Products Corp
  • Bries Malt & Ingredients Co.

Explore Horizon Databook – The world's most expansive market intelligence platform developed by Grand View Research.

Conclusion

The global barley market is expected to experience steady growth through 2030, driven by strong demand from the brewing, distilling, animal feed, and food industries. Rising consumption of craft and premium beverages, increasing livestock production, and growing interest in plant-based diets are key factors shaping market expansion. With Europe maintaining its leadership position and ongoing innovations in barley breeding and sustainable product development, the market is well positioned for continued growth over the forecast period.

Balsa Wood Market 2030: Trends Shaping the Future of Lightweight Materials

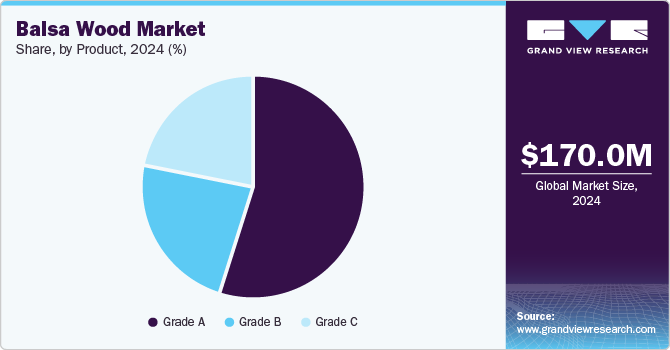
The global balsa wood market was valued at USD 170.0 million in 2024 and is expected to expand to USD 245.3 million by 2030, registering a CAGR of 6.3% during the period from 2025 to 2030. Market growth is primarily supported by the increasing use of balsa wood across industries such as wind energy, marine, and construction.

Balsa Wood Market Share, By Product, 2024 (%)

Balsa wood is highly regarded for its lightweight nature, high strength, and excellent thermal insulation properties, making it particularly suitable for applications that require a superior strength-to-weight ratio. One of the most significant growth drivers is the rapid expansion of the wind energy sector, where balsa wood is widely utilized as a core material in wind turbine blades. As governments worldwide continue to invest heavily in renewable energy to achieve sustainability and carbon reduction goals, demand for efficient and durable materials such as balsa wood is steadily increasing. Additionally, the construction sector’s growing emphasis on environmentally sustainable building materials has accelerated the adoption of balsa wood in insulation systems and structural panels due to its renewable and eco-friendly characteristics.

Furthermore, advancements in wood processing technologies and composite manufacturing techniques have enhanced the durability, quality, and performance of balsa wood products. These improvements have broadened the material’s range of applications and attracted new end users, thereby contributing to overall market growth. The increasing availability of plantation-grown balsa wood, particularly in regions like Ecuador and Papua New Guinea, has helped ensure a reliable and sustainable supply chain, further supporting its adoption in global markets.

Order a free sample PDF of the Balsa Wood Market Intelligence Study, published by Grand View Research.

Key Market Trends & Insights

  • Regional Insights: The Asia Pacific region led the global balsa wood market in 2024, accounting for approximately 39.9% of total revenue. This dominance is largely attributed to the rapid development of wind energy infrastructure in countries such as China, India, and Australia, where government-backed investments in renewable energy are accelerating demand for balsa wood used in high-performance wind turbine blades.
  • End-Use Insights: The wind energy segment held the largest market share in 2024, contributing 45.1% of total revenue. This leadership is driven by the growing global focus on renewable energy generation. Balsa wood’s high strength-to-weight ratio and inherent stiffness make it an ideal core material for wind turbine blades, where lightweight yet durable structures are essential for maximizing efficiency and operational performance.
  • Product Insights: The Grade A balsa wood segment dominated the market in 2024, capturing a revenue share of 53.3%. This growth is fueled by rising demand for premium-quality, lightweight materials in industries such as marine and wind energy. Grade A balsa wood offers superior density consistency, minimal defects, and excellent mechanical strength, making it highly suitable for precision-driven and performance-critical applications, particularly in renewable energy infrastructure.

Market Size & Forecast

  • 2024 Market Size: USD 170.0 Million
  • 2030 Projected Market Size: USD 245.3 Million
  • CAGR (2025-2030): 6.3%
  • Asia Pacific: Largest market in 2024

Key Companies & Market Share Insights

Major players in the balsa wood market are actively implementing strategies such as capacity expansions, strategic partnerships, and geographic diversification to strengthen their market position and enhance product availability. These initiatives are expected to play a crucial role in supporting sustained market growth over the forecast period.

Key Players

  • 3A Composites GmbH
  • Schweiter Technologies AG
  • DIAB International AB
  • CoreLite Inc.
  • Gurit Holding AG
  • Carbon-Core Corp.
  • Pacific Coast Marine
  • Pontus Wood Group
  • BALTEK Corporation

Explore Horizon Databook – The world's most expansive market intelligence platform developed by Grand View Research.

Conclusion

The global balsa wood market is poised for steady growth through 2030, driven by its increasing adoption in wind energy, construction, and marine applications. Rising investments in renewable energy, advancements in manufacturing technologies, and the availability of sustainably sourced balsa wood are collectively reinforcing market expansion. With strong demand from Asia Pacific and continued emphasis on high-performance, eco-friendly materials, the balsa wood market is expected to maintain a positive growth trajectory over the coming years.

Autonomous Vehicle Market 2030: Driving into the Future

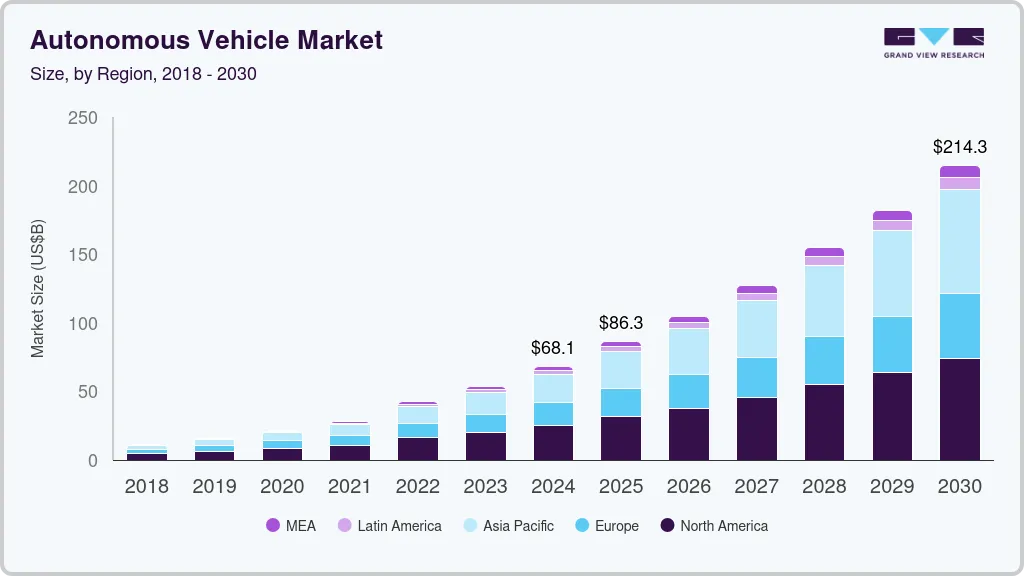
The global autonomous vehicle market was valued at USD 68.09 billion in 2024 and is expected to grow significantly, reaching USD 214.32 billion by 2030, at a CAGR of 19.9% from 2025 to 2030. This strong growth is primarily driven by rising customer demand for advanced technologies, increasing emphasis on road safety, enhanced vehicle connectivity, and rapid progress in artificial intelligence and sensor technologies.

Autonomous vehicle market size by region, and growth forecast (2025-2030)

These technological advancements improve vehicle safety, reliability, and performance, while also broadening the range of autonomous vehicle applications. Autonomous solutions are increasingly being deployed across sectors such as logistics, transportation, ride-sharing, and delivery services. In addition, improved cost efficiency resulting from technological innovation is making autonomous systems more attractive to businesses seeking competitive and scalable mobility solutions.

Industries adopting self-driving technologies demonstrate a growing readiness to integrate advanced innovations into their operations. As organizations experience higher efficiency, lower operational costs, and improved safety outcomes, investment and adoption of autonomous vehicle technology continue to accelerate across multiple sectors. A notable development in this space is Hyundai Motor Group’s launch of “Pleos,” a new mobility software brand and platform aimed at advancing software-defined vehicles (SDVs). Introduced at the Pleos 25 developer conference in Seoul, Pleos combines vehicle operating systems, cloud infrastructure, autonomous driving capabilities, and fleet management solutions to enhance connected mobility experiences. Hyundai Motor Group also announced plans to introduce Level 2+ autonomous driving by 2027 and unveiled the Next Urban Mobility Alliance (NUMA) to promote public–private collaboration for smart, cloud-based urban mobility solutions.

Order a free sample PDF of the Autonomous Vehicle Market Intelligence Study, published by Grand View Research.

Key Market Trends & Insights

  • Regional Outlook: North America led the global autonomous vehicle market in 2024, accounting for over 37.1% of the total market share. The region’s advanced infrastructure, particularly in technology hubs such as Silicon Valley, California, supports large-scale testing and deployment of autonomous vehicles. Strong consumer openness to new technologies and favorable regulatory and innovation ecosystems further support market growth in this region.
  • By Vehicle Type: The passenger vehicle segment dominated the market in 2024, contributing 69% of global revenue. Increasing consumer demand for safer, more convenient, and efficient transportation has fueled interest in autonomous passenger vehicles. Continuous improvements in sensors, artificial intelligence, and vehicle connectivity have enhanced the feasibility and reliability of these vehicles, boosting consumer confidence and adoption.
  • By Application: The transportation segment held the largest revenue share at 85.6% in 2024, driven by its substantial potential for operational efficiency and innovation. Autonomous vehicles are transforming the movement of people and goods by improving safety, optimizing logistics, and reducing costs. Industries such as logistics, shipping, and ride-sharing are increasingly adopting autonomous technologies to meet rising demand for reliable and efficient transportation solutions.
  • By Level of Autonomy: Level 1 autonomy accounted for the highest revenue share in 2024. Features such as adaptive cruise control and lane-keeping assistance are widely adopted due to their affordability, ease of integration, and safety benefits. Automakers frequently offer these systems as standard or optional features, making them highly accessible and reinforcing their dominance in the market.

Market Size & Forecast

  • 2024 Market Size: USD 68.09 Billion
  • 2030 Projected Market Size: USD 214.32 Billion
  • CAGR (2025-2030): 19.9%
  • North America: Largest market in 2024
  • Asia Pacific: Fastest growing market

Key Companies & Market Share Insights

The autonomous vehicle market is highly competitive, with a limited number of global players holding significant market shares. Companies are focusing on innovation, strategic partnerships, and pilot projects to strengthen their market presence. For example, in May 2024, Renault Group partnered with WeRide to trial electric and autonomous shuttles for access to the Roland-Garros stadium, demonstrating the readiness of autonomous public transport technologies.

  • Tesla, Inc.: Tesla is a leading electric vehicle and clean energy company with strong capabilities in autonomous driving technology. Its vehicles feature advanced driver-assistance systems supported by the Full Self-Driving (FSD) software, offering functions such as automated lane changes, traffic-aware cruise control, and urban navigation. Tesla continuously enhances its autonomous features through over-the-air software updates and equips its vehicles with hardware designed for future autonomy, supported by a global Supercharger network.
  • Zoox (Amazon subsidiary): Zoox focuses on fully autonomous, purpose-built electric vehicles for ride-hailing services. Its bi-directional vehicles are designed without steering wheels or manual controls and target Level 5 autonomy, requiring no human intervention. Zoox utilizes advanced lidar, radar, and camera systems combined with powerful onboard computing to navigate complex urban environments. The company operates test fleets in cities including San Francisco, Las Vegas, and Seattle and is among the few authorized to test driverless vehicles without safety drivers in California.

Key Players

  • AUDI AG.
  • Ford Motor Company
  • Mercedes-Benz Group
  • Nuro, Inc.
  • Pony.ai
  • Tesla
  • Toyota Kirloskar Motor
  • Volkswagen Group
  • Waymo LLC
  • Zoox, Inc.

Explore Horizon Databook – The world's most expansive market intelligence platform developed by Grand View Research.

Conclusion

The autonomous vehicle market is poised for substantial growth, supported by rapid technological advancements, increasing consumer acceptance, and expanding applications across transportation and logistics sectors. With a projected market size of USD 214.32 billion by 2030 and a strong CAGR of 19.9%, autonomous mobility is transitioning from experimental deployment to large-scale commercialization. Continued investments by leading companies, supportive infrastructure development, and advancements in AI and connectivity will play a crucial role in shaping the future of autonomous transportation, making it safer, more efficient, and increasingly integral to global mobility systems.